Official document 4113/QNI-QLDN2 Issued by the Quang Ninh Provincial Tax Department on August 17, 2026, to resolve difficulties regarding tax policies for foreign contractors and value-added tax on construction contracts and the supply of machinery and equipment to export processing enterprises. This is in the context of existing legal documents such as... Decree 320/2025/ND-CP, Circular 20/2026/TT-BTC, Decree 252/2026/ND-CP and Circular 89/2026/TT-BTC In practice, understanding the guiding principles in this document will help businesses comply with regulations and optimize tax costs.
In practice, financial management in foreign-invested enterprises (FDI) and export processing enterprises (EPEs) shows that transactions involving the purchase of machinery and equipment with installation services often carry the risk of tax assessment or administrative penalties due to incorrect declaration timing. Circular 4113/QNI-QLDN2 serves as an important operational guide, helping accounting departments accurately handle withholding tax obligations and submit tax declarations for 2026.
Summary of key points in Official Letter 4113/QNI-QLDN2
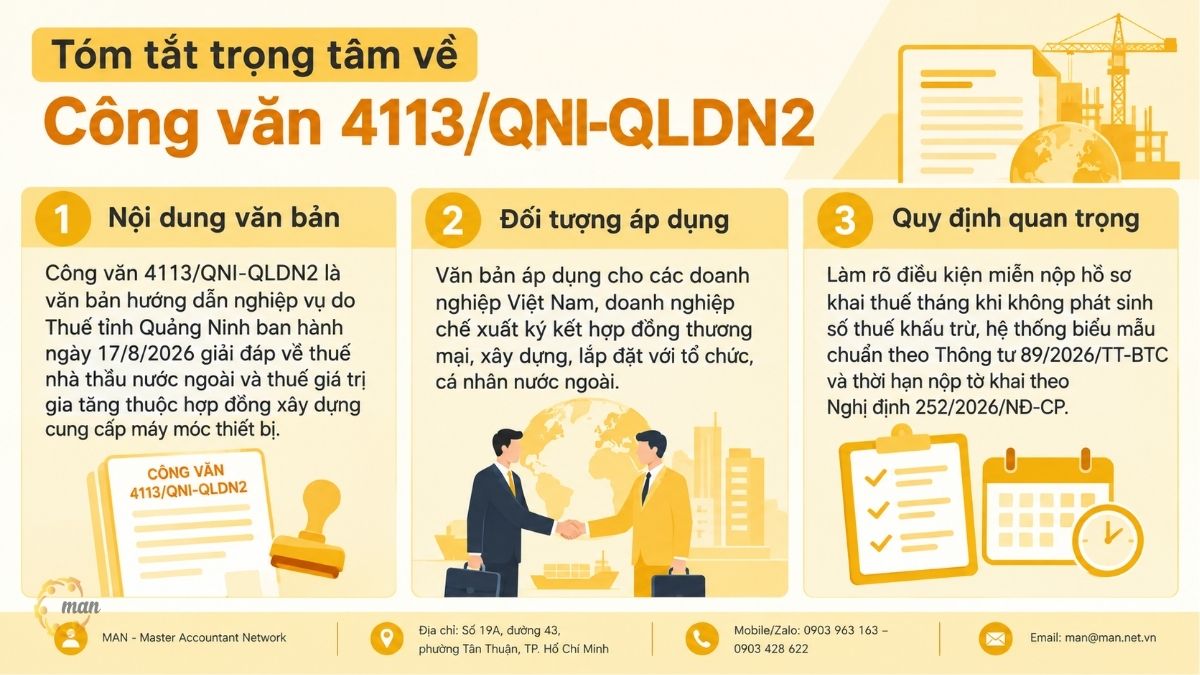
- Official document 4113/QNI-QLDN2 is a professional guidance document issued by the Quang Ninh Provincial Tax Department on August 17, 2026, providing clarification on foreign contractor tax and value-added tax related to construction contracts for the supply of machinery and equipment.
- This document applies to Vietnamese enterprises and export processing enterprises that sign commercial, construction, and installation contracts with foreign organizations and individuals.
- The regulations clarify the conditions for exemption from filing monthly tax returns when no withholding tax arises, the standard form system according to Circular 89/2026/TT-BTC, and the deadline for filing tax returns according to Decree 252/2026/NĐ-CP.
The legal context for issuing Official Letter 4113/QNI-QLDN2 and its role in tax administration in 2026.
The period 2025-2026 marks a major reform in Vietnam's tax management system with the introduction of a comprehensive set of new legal regulations. This change requires finance and accounting professionals to continuously update their knowledge to ensure compliance. Circular 4113/QNI-QLDN2 was issued to directly address practical issues arising from the operations of businesses in Quang Ninh province.
In their business operations, export processing enterprises frequently import machinery, equipment, and raw materials from foreign traders through bonded warehouses or free trade zones. Simultaneously, factory expansion projects often involve turnkey construction and machinery installation contracts. Accurately determining contractor tax and value-added tax obligations for these complex transaction chains is a top priority in risk management.
The core legal grounds cited in Official Letter 4113/QNI-QLDN2 include:
- Clause 3, Article 12 of Decree 320/2025/ND-CP stipulates the subjects liable to contractor tax.
- Clause 2, Article 7 of Circular 20/2026/TT-BTC provides guidance on the obligation to submit monthly tax declarations.
- Clause 8 of Article 11 and Article 10 Decree 252/2026/ND-CP Regulations specify the deadline for filing tax returns.
- Appendix 1 is issued herewith Circular 89/2026/TT-BTC Regulations detailing the tax declaration dossier for foreign contractors.
From the perspective of MAN – Master Accountant Network, timely access to guidance documents such as Circular 4113/QNI-QLDN2 helps businesses proactively negotiate international contracts, avoiding unexpected costs arising from misunderstandings regarding tax obligations paid on behalf of others.
Guidance on foreign contractor tax according to Official Letter 4113/QNI-QLDN2
Regulations on exemption from monthly contractor tax declaration filing are outlined in Official Letter 4113/QNI-QLDN2.
The most important solution in Official Letter 4113/QNI-QLDN2 lies in the guidance on handling cases where businesses declare and pay taxes on behalf of others on a monthly basis but do not generate any deductible tax amount during the period.
Based on Clause 2, Article 7 of Circular 20/2026/TT-BTC, if a business is currently paying value-added tax and corporate income tax on behalf of a foreign contractor using the monthly tax declaration method, and no tax deductions arise in that month, then... Foreign contractors are not required to file tax returns..
This regulation applies specifically to cases where foreign traders sell goods that are raw materials, supplies, or components from bonded warehouses or free trade zones for import into Vietnam to serve the production of export goods or processing of export goods under signed contracts.
This guideline alleviates the significant administrative burden on export processing enterprises and export-oriented businesses. Accounting departments no longer have to prepare blank declarations (with no data generated) monthly, minimizing the risk of late payment penalties due to forgetting to submit declarations that do not generate tax obligations.
Analysis of contractor tax obligations on income generated in Vietnam.
Foreign organizations and individuals conducting business or generating income in Vietnam based on contracts or agreements with Vietnamese organizations and individuals are subject to foreign contractor tax. This tax comprises two main components: value-added tax and corporate income tax.
In the case of a contract for the supply of machinery and equipment that includes services performed in Vietnam such as consulting, supervision, installation, commissioning, maintenance, and training:
- Income from services rendered in Vietnam is subject to mandatory declaration and payment of contractor tax.
- If the contract separately specifies the value of machinery and equipment and the value of services, contractor tax will be applied to each part separately according to the stipulated rates.
- If the contract does not separate the value of machinery and services, the tax authorities will apply a % rate. corporate income tax and VAT across the entire contract value.
Experts at MAN, with 30 years of experience, note that the failure to clearly separate the value of ancillary services in machinery and equipment purchase contracts is the leading reason why businesses are subject to significant corporate income tax arrears during tax audits.
Details of the tax declaration dossier for foreign contractors according to Circular 89/2026/TT-BTC are cited in Official Letter 4113/QNI-QLDN2.
To properly implement the directives in Official Letter 4113/QNI-QLDN2, businesses need to refer to Appendix 1 issued with Circular 89/2026/TT-BTC to prepare the correct and complete documentation for each specific case.
Direct method (Ratio of % to revenue)
The most common direct method applied is when the Vietnamese party deducts and pays taxes on behalf of the foreign contractor. The contractor pays VAT directly on revenue and corporate income tax at a rate of 1% VAT to 3% VAT on taxable revenue.
Tax returns can be filed on a per-transaction or monthly basis (if multiple transactions occur within a month):
- Foreign contractor tax return form Form No. 01/NTNN (Applicable to the Vietnamese party withholding and paying taxes on behalf of the other party).
- A certified copy of the contractor's contract or subcontractor's contract, signed by the taxpayer (only to be submitted with the first tax return for the contract).
Tax return documents required upon completion of a contractor contract:
- Foreign contractor tax return form Form No. 02/NTNN.
- Appendix: List of foreign contractors Form No. 02-1/NTNN.
- Appendix: List of subcontractors participating in the contractor's contract. Form No. 02-2/NTNN.
Mixed method
The mixed method is applied when a foreign contractor pays VAT using the deduction method, but pays corporate income tax at a rate of 1% VAT to 3% VAT calculated on taxable revenue.
Tax returns can be filed on a transaction-by-transaction or monthly basis:
- Foreign contractor tax return form Form No. 03/NTNN.
- Copies of the contractor's contract and subcontractor's contract (to be submitted with the first tax declaration for the contract).
Tax return documents upon contract termination:
- Foreign contractor tax return form Form No. 04/NTNN.
- Appendix: List of subcontractors participating in the contractor's contract. Form No. 02-2/NTNN.
Deduction method
The deduction method applies when a foreign contractor has a permanent establishment in Vietnam, the contract term is 183 days or more, and the contractor adheres to Vietnamese accounting standards.
- Value Added Tax (VAT) declaration: Declare VAT according to the general regulations applicable to business organizations as specified in point 4, Appendix 1 of Circular 89/2026/TT-BTC.
- Corporate income tax declaration: Declare corporate income tax in accordance with the provisions of point 6, Appendix 1 of Circular 89/2026/TT-BTC.
Tax return forms for specific industries
Circular 89/2026/TT-BTC also stipulates separate forms for foreign traders operating in the fields of transportation, aviation, and insurance:
Foreign airlines (Quarterly tax filing):
- Corporate income tax return form for foreign airlines Form No. 01/HKNN.
- Copies of the main contractor's contract and subcontractor's contract (to be submitted with the initial declaration).
Foreign shipping companies (Annual tax return):
- Corporate income tax return form for foreign transport companies Form No. 01/VTNN.
- Appendix to the statement of international transport income. Form No. 01-1/VTNN (Applicable to shipping companies).
- Appendix to the statement of international transport income. Form No. 01-2/VTNN (Applies to cases of seat swapping).
- Containerized revenue statement Form No. 01-3/VTNN.
Foreign reinsurance organizations (Quarterly tax filing):
- Corporate income tax return form for foreign reinsurance organizations Form No. 01/TBH.
- Reinsurance contract addendum, reinsurance certificate Form No. 01-1/TBH.
The deadline for submitting contractor tax returns under Decree 252/2026/ND-CP is stated in Official Letter 4113/QNI-QLDN2.
Precisely defining the deadline for filing tax returns helps businesses proactively plan their finances and avoid administrative violations. According to Article 10 of Decree 252/2026/ND-CP, the deadline for filing tax returns for contractor tax is clearly defined for each declaration method.
Deadline for submitting periodic tax returns
Declare on a case-by-case basis:
- The deadline for filing tax returns is: Day 10 from the day following the date the tax liability arises.
- Special case: Except for cases where tax declaration and payment must be made before the tax authority issues an electronic invoice with a code for each transaction, as stipulated in point b, clause 3, Article 26 of the Law on Tax Administration.
File monthly:
- The deadline for filing tax returns is: Day 20 of the month following the month in which the tax liability arises.
Filing on a quarterly basis:
- The deadline for filing tax returns is: last day of the first month of the quarter following the quarter in which the tax liability arises.
File by year:
- The deadline for filing tax returns is: the last day of the first month of the following calendar year or fiscal year.
Deadline for submitting tax return documents
When a contractor's contract ends or is terminated, the party paying the tax on their behalf must complete the settlement procedures to determine the amount of tax payable.
Based on point a, clause 5, Article 10 of Decree 252/2026/ND-CP:
- The deadline for submitting tax return documents is no later than: the last day of the third month from the date of the end of the tax settlement period or the termination of the contractor's contract.
Businesses should note that the contract termination date is calculated from the date both parties accept, finalize the contract, or complete the service provision and handover of the project.
VAT policy for construction contracts supplying machinery to export processing enterprises.
Construction, supply, and installation contracts for machinery and equipment for export processing enterprises (EPEs) have unique characteristics due to the legal status of EPEs, which are considered duty-free zones.
Conditions for applying VAT rate 0%
According to current regulations mentioned in Official Letter 4113/QNI-QLDN2, goods and services supplied to export processing enterprises are subject to VAT rate 0% if they meet the following conditions:
- There are contracts for the sale, processing of goods, or provision of services signed with businesses in the free trade zone.
- There is proof of payment for goods and services through the bank.
- A customs declaration form is required (for the goods being supplied).
For construction and installation services directly serving the production activities of export processing enterprises operating within the free trade zone, the service provider is subject to VAT rate 0%.
VAT treatment for mixed equipment supply and construction contracts.
In practice, foreign or domestic contractors often sign lump-sum contracts that include both the supply of imported machinery and equipment and construction and installation services at the export processing enterprise's factory.
Businesses need to be aware of the need to clearly separate these two parts:
- Imported machinery and equipment: Customs procedures for import into the free trade zone are required, and they are exempt from import VAT or subject to the VAT rate of 0% if all conditions are met.
- Construction and installation services in Vietnam: Subject to contractor tax. VAT liability depends on the tax payment method used by the contractor and the legal status of the beneficiary.
The solution from MAN – Master Accountant Network recommends that businesses, when negotiating mixed contracts, must separate the value of imported goods and the value of construction and installation services. This ensures transparency in calculating VAT and corporate income tax for the contractor, avoiding double taxation or taxation on the entire contract value.
Summary table comparing records and deadlines for contractor tax declaration in 2026
The table below summarizes all the forms and deadlines for declaring taxes for foreign contractors, as quoted from Official Letter 4113/QNI-QLDN2, Circular 89/2026/TT-BTC, and Decree 252/2026/NĐ-CP:
| Tax payment methods | Type of declaration period | Applicable application forms (Circular 89/2026/TT-BTC) | Deadline for submitting applications (Decree 252/2026/ND-CP) |
| Direct | Each occurrence | Form 01/NTNN + Copy of the Contract (first copy) | No later than the 10th day from the day following the date the tax liability arises. |
| Direct | By month | Form 01/NTNN (Exempt from submission if no deductions arise according to Official Letter 4113/QNI-QLDN2) | No later than the 20th day of the month following the month in which the obligation arises. |
| Direct | Contract settlement | Form 02/NTNN, Appendix Form 02-1/NTNN, Appendix Form 02-2/NTNN | No later than the last day of the third month from the contract termination date. |
| Mixed | Once a month | Form 03/NTNN + Copy of the Contract (first copy) | The 10th day (of the transaction) or the 20th day of the following month (the start of the month). |
| Mixed | Contract settlement | Form 04/NTNN, Appendix Form 02-2/NTNN | No later than the last day of the third month from the contract termination date. |
| Deduction | Month / Quarter | VAT and corporate income tax returns are prepared according to the general regulations in points 4 and 6 of Appendix 1. | The 20th day of the following month (month opening) or the last day of the first month of the following quarter (quarter opening) |
| Air | Quarterly | Form 01/HKNN + Copy of the Contract (first copy) | No later than the last day of the first month of the quarter following the quarter in which the event occurs. |
| Transportation | Annual settlement | Form 01/VTNN, Appendix Form 01-1/VTNN, Form 01-2/VTNN, Form 01-3/VTNN | No later than the last day of the first month of the following calendar/fiscal year. |
| Reinsurance | Quarterly | Form 01/TBH, Appendix Form 01-1/TBH | No later than the last day of the first month of the quarter following the quarter in which the event occurs. |
Practical Case Study: Analysis of Contractor Tax and Machinery Contract Handling in Quang Ninh
To clarify how to apply Circular 4113/QNI-QLDN2 in practice, let's analyze the real-world situation of an export processing enterprise implementing an investment project in 2026.
Business situation
Precision Electronics Co., Ltd. (Foreign-invested enterprise 100% in Song Khoai Industrial Park, Quang Ninh) signed a contract to purchase and install a production line worth USD 10,000,000 with Global Tech Inc. (headquartered in South Korea).
The contract details include:
- Supply of machinery and automation equipment imported from South Korea: USD 8,500,000. Goods will be delivered to the Hai Phong bonded warehouse before import procedures are completed at the factory.
- Design, construction, installation, commissioning, and operation training services for a factory in Quang Ninh: USD 1,500,000.
Global Tech Inc. chose the direct tax payment method, entrusting Precision Electronics with deducting and paying contractor tax on its behalf.
Methods of handling and results of applying the regulations
In April 2026, Precision Electronics imported the entire batch of machinery worth USD 8,500,000 from the bonded warehouse to its factory. The installation services, valued at USD 1,500,000, have not yet been inspected and paid for.
Tax processing for April 2026:
- Based on Official Letter 4113/QNI-QLDN2 and Clause 2, Article 7 of Circular 20/2026/TT-BTC, for the batch of machinery worth USD 8,500,000 imported from bonded warehouses for export production, since no tax deduction for the service portion occurred in April, Precision Electronics No need to submit Form 01/NTNN for the April 2026 term.
Tax treatment when paying for installation services (June 2026):
- Upon completion of acceptance testing and transfer of payment of USD 1,500,000 to Global Tech Inc, Precision Electronics deducted contractor corporate income tax for the service at a rate of 5%.
- Corporate income tax paid by the contractor = USD 1,500,000 x 5% = USD 75,000.
- Due to transactions occurring in June, the deadline for submitting Form 01/NTNN along with a copy of the contract is July 20, 2026 at the latest.
Financial impact:
If the contract does not separate the value of the $1,500,000 service and the $8,500,000 machinery, the tax authorities will apply the corporate income tax rate 2% to the entire $10,000,000 contract. This would increase the amount of tax payable to $200,000. Accurately separating the contract values from the outset helps the business optimize its legal tax expenses by $125,000.
Expert analysis from MAN – Master Accountant Network on contractor tax risks in 2026.
During our work with hundreds of FDI and manufacturing businesses in Vietnam, our experts have identified many legal blind spots that businesses frequently encounter.
Confusion between Incoterms conditions and domestic tax obligations.
A very common mistake made by purchasing departments is assuming that contracts for the purchase of machinery signed under CIF or FOB terms do not incur contractor tax. Conversely, if signed under DDP terms, contractor tax is automatically payable on the entire value.
Experts at MAN, with 30 years of experience, note that the nature of contractor tax depends on whether the foreign organization performs services related to the goods within Vietnamese territory. Even with an FOB contract, if the seller sends experts to Vietnam to provide installation guidance and training, the cost of that service (or the entire contract if it cannot be separated) is still subject to contractor tax.
Neglecting the procedure of submitting settlement documents when terminating a contract.
Many businesses declare and pay contractor tax in full with each payment to foreign partners, but neglect to file a final contractor tax return upon completion of the contract.
According to Decree 252/2026/ND-CP, the deadline for submitting tax settlement documents is the last day of the third month from the date the contract ends. The lack of tax settlement declaration forms 02/NTNN or 04/NTNN causes data on the tax authority's centralized tax management system to be suspended. This creates significant difficulties for businesses when they later carry out VAT refund procedures or procedures for closing their tax code or dissolving the company.
To thoroughly address the aforementioned risks, the solution from MAN – Master Accountant Network supports businesses in reviewing their entire international trade contract system, standardizing payment document preparation processes, and representing businesses in carrying out a complete package of accurate tax declaration and settlement procedures with the authorities.
Conclude
Official document 4113/QNI-QLDN2 of 2026 from the Quang Ninh Provincial Tax Department provides timely and practical guidance, clarifying business concerns regarding the obligation to submit contractor tax declarations and VAT policies for construction contracts. The accurate application of the forms system according to Circular 89/2026/TT-BTC, along with the deadlines for declaration and settlement stipulated in Decree 252/2026/NĐ-CP, provides a solid foundation for businesses to maintain legal compliance and financial security.
Tax services at MAN – Master Accountant Network
- Tax accounting services
- Tax consulting services
- Tax settlement services
- Tax reporting services
- VAT refund service
Service contact information at MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network, CPA Vietnam with over 30 years of experience in accounting, auditing, taxation, and corporate financial consulting.
Frequently Asked Questions about Official Document 4113/QNI-QLDN2 (FAQ)
Which agency issued Official Document 4113/QNI-QLDN2 and to whom does it apply?
Official document 4113/QNI-QLDN2 issued by the Quang Ninh Provincial Tax Department on August 17, 2026. This document applies to Vietnamese enterprises and export processing enterprises that have transactions involving the purchase and sale of goods and components, imports from bonded warehouses, or construction and machinery installation contracts with foreign contractors.
If a business files monthly contractor tax returns but does not incur any deductions, is it still required to submit a tax return?
According to Official Letter 4113/QNI-QLDN2 and Circular 20/2026/TT-BTC, businesses that pay taxes on behalf of others on a monthly basis are not required to submit contractor tax declarations if there are no tax deductions for goods imported from bonded warehouses or free trade zones for the production of export goods during the month.
What is the deadline for submitting contractor tax returns for each transaction?
According to Clause 1, Article 10 of Decree 252/2026/ND-CP, the deadline for submitting contractor tax declaration documents for each transaction is no later than the 10th day following the date the tax liability arises.
What forms are included in the contractor tax settlement dossier using the direct method?
According to Circular 89/2026/TT-BTC, the settlement dossier includes: Settlement Declaration Form No. 02/NTNN, Appendix List of Foreign Contractors Form No. 02-1/NTNN, and Appendix List of Subcontractors Form No. 02-2/NTNN.
Are construction contracts for supplying machinery to export processing zones eligible for VAT rate 0%?
The value of construction and machinery installation services provided to export processing enterprises is subject to VAT rate 0% if all conditions regarding contracts, non-cash bank payment documents, and customs declarations (for machinery and equipment) are met.