

Six tax return forms will be officially replaced and will take effect from July 1, 2026, as stipulated in the regulations. Circular 89/2026/TT-BTC Issued by the Minister of Finance on June 30, 2026. This document provides detailed regulations on several articles of the Law on Tax Administration and Decree 252/2026/ND-CP. Circular 89/2026/TT-BTC directly replaces the forms currently in use under Circular 50/2026/TT-BTC and Circular 18/2026/TT-BTC. This is a change that all business households, individual business owners, and tax-filing organizations need to be aware of to avoid errors when preparing documents.
Many accountants and business owners still confuse the old and new forms, leading to rejected or late submissions. This article, compiled from a professional perspective, provides valuable insights. MAN – Master Accountant Network, A tax, accounting, and auditing consulting firm with over 30 years of practical experience in Vietnam has comprehensively systematized the list of 6 replaced forms, their applicable entities, transition timelines, and risks businesses need to avoid when filing.
A summary of the key points regarding the 6 tax return forms that will be replaced.
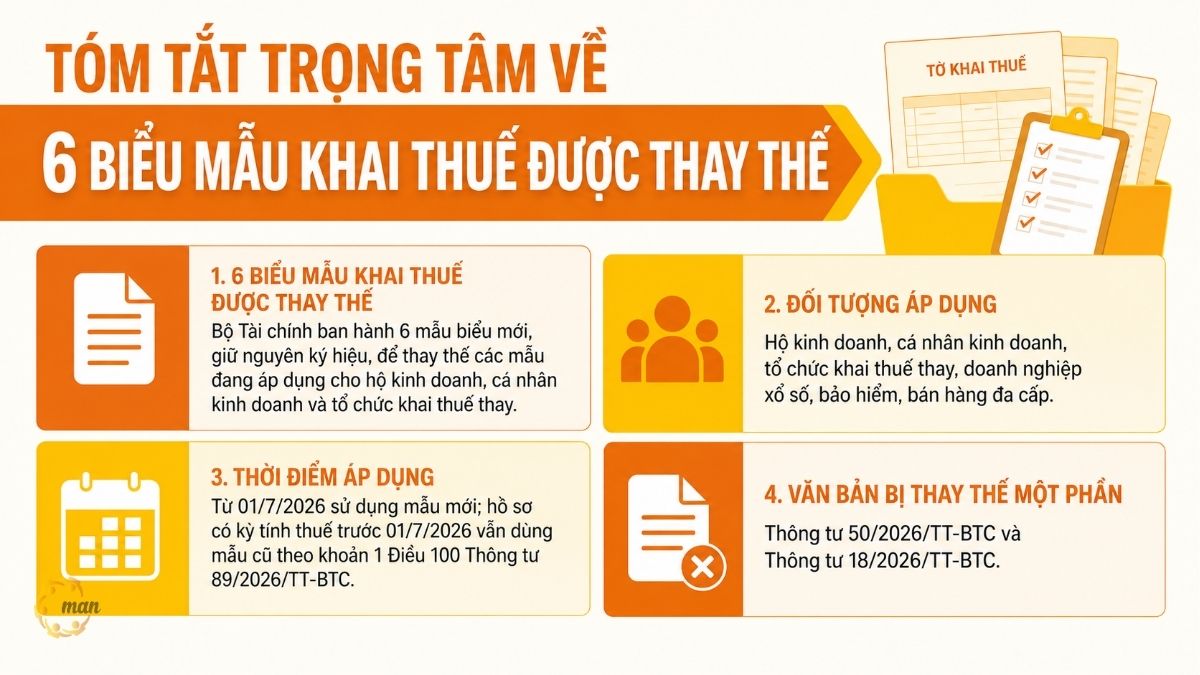
- The Ministry of Finance has issued six new tax declaration forms, retaining the same symbols, to replace the forms currently used by business households, individual businesses, and organizations filing taxes on behalf of others.
- Legal basis: Clause 5, Article 99 of Circular 89/2026/TT-BTC, effective from July 1, 2026.
- Applicable entities: household businesses, individual businesses, organizations filing tax returns on behalf of others, lottery companies, insurance companies, and multi-level marketing companies.
- Effective date: The new form will be used from July 1, 2026; tax records with tax periods prior to July 1, 2026 will still use the old form as per Clause 1, Article 100 of Circular 89/2026/TT-BTC.
- The following documents have been partially superseded: Circular 50/2026/TT-BTC and Circular 18/2026/TT-BTC.
What are the 6 tax return forms that have been replaced? Definition and legal basis.
According to Clause 5, Article 99 of Circular 89/2026/TT-BTC, 6 tax return forms have been replaced. These are the forms and schedules used in tax management for household businesses, individual businesses, and organizations filing taxes on behalf of others. The Ministry of Finance has issued new versions of these forms in Appendix I accompanying Circular 89/2026/TT-BTC, replacing the forms currently in use under Circular 50/2026/TT-BTC and Circular 18/2026/TT-BTC.
The names and model numbers of these six models have essentially remained the same. However, from that point onwards... Circular 89/2026/TT-BTC Effective now, taxpayers and tax-filing organizations are required to use the correct new version.
In other words, this isn't about adding entirely new forms, but rather about ongoing activities. Updating and consolidating the legal framework. regarding tax declaration forms according to the Tax Administration Law and Decree 252/2026/ND-CP. This is a common misconception among accountants, who often assume that simply changing the document number is sufficient without needing to re-upload the form.
Legal basis for determining the replacement of tax return forms:
- Circular 89/2026/TT-BTC: issued on June 30, 2026, effective from July 1, 2026, provides detailed regulations on a number of articles of the Law on Tax Administration and Decree 252/2026/ND-CP.
- Clause 5 of Article 99 of Circular 89/2026/TT-BTC specifically lists 6 forms that are replaced and the corresponding replacement documents.
- Clause 1, Article 100 of Circular 89/2026/TT-BTC: stipulates the application of forms according to the tax period, i.e., a transitional provision.
- Decree 252/2026/ND-CP: the original document that Circular 89/2026/TT-BTC guides its implementation.
Why are the six replacement tax forms important for businesses?
A tax return filed using the wrong form, even if the information is accurate, still risks being deemed invalid by the tax authorities. For household businesses and individual entrepreneurs, this can lead to delayed filing, late payment penalties, or the need for further explanations. Therefore, familiarizing yourself with the six replacement tax return forms is not only a matter of compliance but also directly impacts the progress and costs of tax processing for businesses.
From this perspective MAN – Master Accountant Network, Based on our experience assisting numerous businesses and organizations in filing tax returns in major cities, the transition period between the old and new forms is always the most prone to errors. Experts at MAN, with over 30 years of experience, advise businesses to review their entire filing process as soon as the new circular is published, rather than waiting until close to the filing deadline.
Which groups will be affected by the six replacement tax forms?
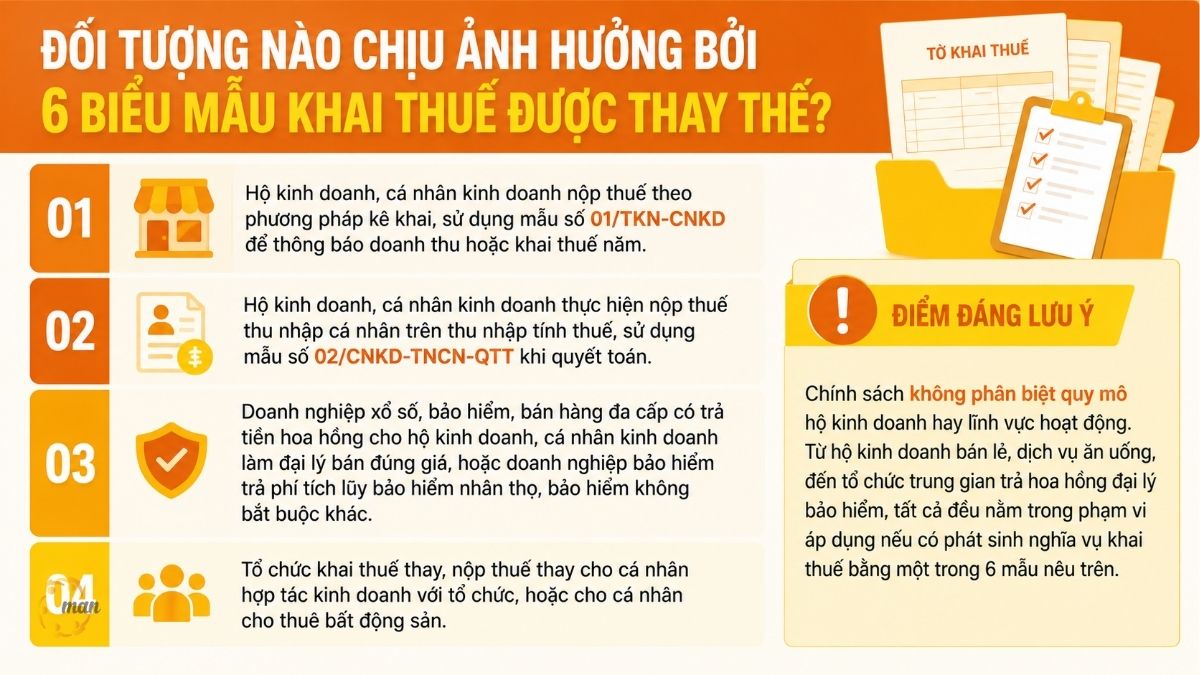
Not all taxpayers will be affected equally. The impact of the form replacement focuses on the following groups:
- Household businesses and individual business owners who pay taxes using the declaration method should use form 01/TKN-CNKD to report revenue or declare annual tax.
- Household businesses and individual business owners pay personal income tax on taxable income, using form 02/CNKD-TNCN-QTT when settling their tax returns.
- Lottery companies, insurance companies, and multi-level marketing businesses pay commissions to household businesses and individual business owners acting as agents selling at the correct price, or insurance companies pay accumulated premiums for life insurance and other non-mandatory insurance.
- An organization prepares and pays taxes on behalf of individuals who cooperate in business with the organization, or on behalf of individuals who lease real estate.
Key point to note: policy regardless of the size of the business or the field of activity. From retail businesses and food service establishments to intermediary organizations paying insurance agent commissions, all are within the scope of application if they have a tax filing obligation using one of the six forms mentioned above.
Here is a detailed list of the 6 tax return forms that will be replaced from July 1, 2026.
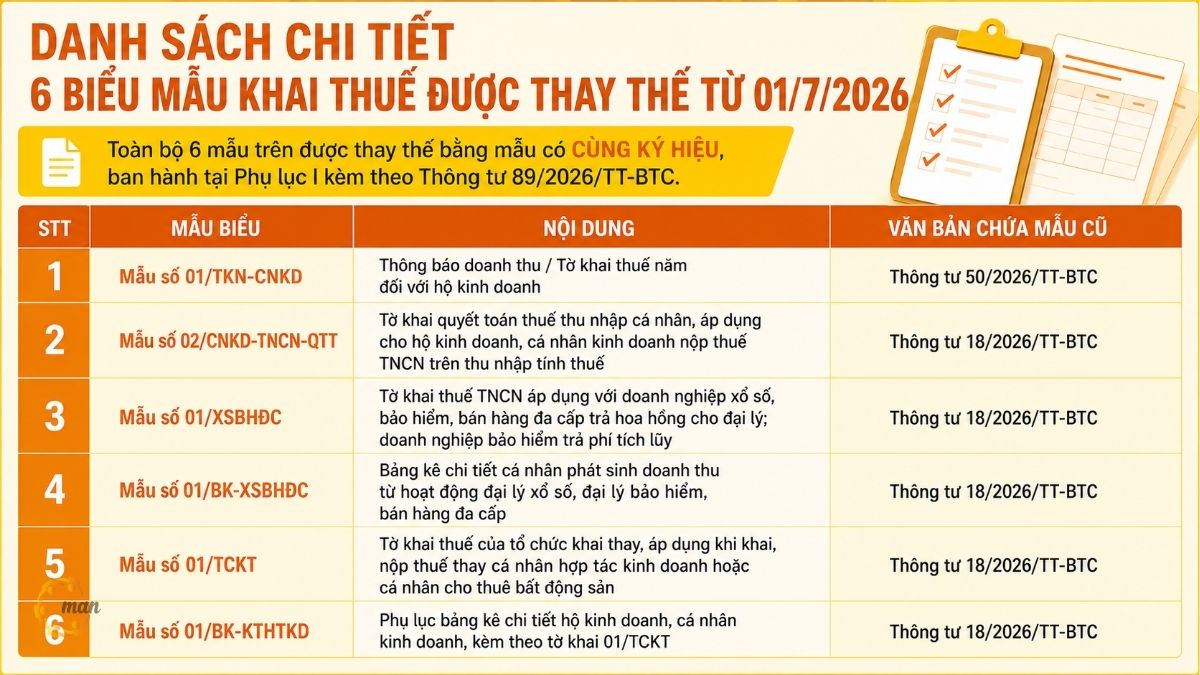
All six of the above samples were replaced with the sample that same symbol, Issued in Appendix I attached to Circular 89/2026/TT-BTC. Businesses and household businesses need to proactively download the new form instead of continuing to use the old archived version on the declaration software.
| STT | Form | Content | The document contains the old template. |
| 1 | Form No. 01/TKN-CNKD | Revenue notification / Annual tax return for household businesses | Circular 50/2026/TT-BTC |
| 2 | Form No. 02/CNKD-TNCN-QTT | Personal income tax return form, applicable to business households and individual business owners paying personal income tax on taxable income. | Circular 18/2026/TT-BTC |
| 3 | Form No. 01/XSBHĐC | Personal income tax return form applicable to lottery companies, insurance companies, multi-level marketing companies paying commissions to agents; and insurance companies paying accumulated premiums. | Circular 18/2026/TT-BTC |
| 4 | Form No. 01/BK-XSBHĐC | Detailed statement of individual revenue generated from lottery agency activities, insurance agency activities, and multi-level marketing. | Circular 18/2026/TT-BTC |
| 5 | Form No. 01/TCKT | This tax return form is for organizations filing on behalf of others, and is applicable when filing and paying taxes on behalf of individuals in business partnerships or individuals who lease real estate. | Circular 18/2026/TT-BTC |
| 6 | Form No. 01/BK-KTHTKD | Appendix: Detailed list of household businesses and individual businesses, attached to declaration form 01/TCKT | Circular 18/2026/TT-BTC |
When should the new template be used, and when can the old template still be used?
This is the question that most accountants are concerned about during the transition period. The principles for application are quite clearly defined:
- From July 1st, 2026, newly filed tax returns must use the 6 forms issued with Circular 89/2026/TT-BTC.
- For tax returns that have Tax period before July 1, 2026, Taxpayers may continue to use the forms applicable before Circular 89/2026/TT-BTC came into effect, as stipulated in Clause 1, Article 100 of this circular.
Simply put, the benchmark for determining which form to apply is not the filing date, but rather the date on which it is used. tax period This creates an obligation. A tax return for the 2025 tax year, but submitted after July 1, 2026, still uses the old form, while returns arising from the tax year of July 1, 2026 onwards must use the new form. This is the detail that... MAN – Master Accountant Network Accountants are advised to carefully review documents before filing to avoid submitting the wrong form for the wrong tax period.
The legal documents related to the six tax return forms have been replaced.
Important note: Article 5 of the Law on Tax Administration stipulates that tax administration includes tax registration, tax declaration, tax calculation, tax deduction, tax payment, tax exemption and reduction, and many other aspects. The issuance of new forms in Circular 89/2026/TT-BTC is within the framework of administrative procedure reform and the application of information technology in tax administration, in accordance with the principles stated in this article.
| Legal documents | Number / Date of Issue | Related content |
| Circular 89/2026/TT-BTC | Ministry of Finance, issued on June 30, 2026, effective July 1, 2026 | Detailed regulations on the Law on Tax Administration and Decree 252/2026/ND-CP; replacing 6 tax declaration forms. |
| Decree 252/2026/ND-CP | Government | Regulations detailing certain provisions and organizational measures, and guidelines for the implementation of the Law on Tax Administration. |
| Tax Administration Law 2019 | Law No. 38/2019/QH14, amended by Clause 1, Article 6 of Law No. 56/2024/QH15 | Principles of tax administration, rights and obligations of taxpayers. |
| Circular 50/2026/TT-BTC | Ministry of Finance | Contains form number 01/TKN-CNKD before being replaced. |
| Circular 18/2026/TT-BTC | Ministry of Finance | Contains the remaining 5 forms before they were replaced. |
What are the current principles governing tax administration?
The replacement of the six tax declaration forms is inseparable from the general principles of tax administration in the State. According to Article 5 of the 2019 Tax Administration Law, as amended by Clause 1, Article 6 of Law No. 56/2024/QH15, current tax administration activities in Vietnam adhere to five core principles.
- Every organization, household, business, and individual has the obligation to pay taxes as prescribed by law.
- Tax authorities and other state agencies tasked with managing tax collection must ensure transparency, fairness, and protect the legitimate rights and interests of taxpayers. Tax officials must process applications within the scope of the taxpayer's provided documents and data, the tax sector's database, and the results of risk management applications, while adhering strictly to their responsibilities and relevant legal regulations.
- Other agencies, organizations, and individuals are responsible for coordinating and participating in tax management in accordance with the law.
- Promote administrative procedure reform and apply modern information technology in tax management; apply tax management principles in accordance with international practices, including the principle that the nature of the activity or transaction determines the tax obligation and the principle of risk management in tax administration.
- Preferential treatment shall be applied when carrying out tax procedures for exported and imported goods, in accordance with customs laws and government regulations.
It can be seen that the issuance of new forms in Circular 89/2026/TT-BTC is a concrete step in implementing the principle of administrative procedure reform and the application of information technology as stated in Clause 4, Article 5 of the Law on Tax Administration.
What does tax administration encompass?
According to Article 5 of the Tax Administration Law, the scope of tax administration is quite broad, encompassing almost the entire lifecycle of a taxpayer's tax obligations, specifically including the following groups of tasks:
- Tax registration; tax declaration, tax calculation, tax deduction; tax payment, late payment penalties, fines; tax assessment; tax refund; handling of overpaid taxes, late payment penalties, and fines.
- Tax exemption, tax reduction, non-taxable, no tax collection; tax debt write-off, tax debt cancellation; waiver of late payment penalties, waiver of fines; calculation or non-calculation of late payment penalties.
- Extension of tax payment deadlines, late payment penalties, and fines; extension of tax return filing deadlines; installment payments of tax arrears; enforcement of administrative decisions on tax management.
- Taxpayer outreach and support; risk management, compliance management; taxpayer information management; invoice and document management.
- Conduct tax audits; implement measures to prevent and combat violations of tax laws; handle administrative violations related to tax management; and resolve complaints and denunciations regarding taxes.
- International cooperation on taxation; tax administration in accordance with international treaties and agreements on taxation to which Vietnam is a member or signatory, and international commitments on taxation.
Of all the content groups above, "tax filing" is the scope directly related to the replacement of the six tax return forms mentioned in this article. According to the assessment... MAN – Master Accountant Network, A thorough understanding of tax management helps businesses and household businesses not only comply with the correct forms and templates but also be more proactive in related stages such as deductions, settlements, or handling complaints if disputes arise with the tax authorities.
Case Study: How do food and beverage businesses in Ho Chi Minh City handle the transition to new forms?
Background
Household business Y, operating in the food and beverage sector in District 3, Ho Chi Minh City, pays taxes using the declaration method and generates stable annual revenue. Prior to July 1, 2026, this household business habitually used form 01/TKN-CNKD according to Circular 50/2026/TT-BTC to periodically report revenue.
How to handle it after July 1, 2026
According to advice from MAN – Master Accountant Network, The accountant in charge of this business household performs three steps: first, accurately determine the tax period for each upcoming tax return to know whether to apply the old or new form; second, download and update the new version of form 01/TKN-CNKD in Appendix I of Circular 89/2026/TT-BTC into the tax declaration software; third, save and compare the old and new forms for explanation if the tax authorities request clarification during the transition period.
Result
Thanks to early review immediately after Circular 89/2026/TT-BTC was issued, business household Y submitted the correct form right from the first tax declaration period after July 1, 2026, without any additional document requests from the tax authorities. This is an example showing that proactively updating forms, even just changing the format, significantly saves processing time compared to waiting for reminders.
Comparison table of old and new forms according to Circular 89/2026/TT-BTC
As can be seen, the biggest change lies not in the name of the form but in the legal basis and the time of application. This is why businesses cannot simply rely on the familiar form name to determine the validity of the documents.
| Criteria | Old form | New form |
| Sample symbols | Remain unchanged (01/TKN-CNKD, 02/CNKD-TNCN-QTT…) | Keep the symbols unchanged. |
| Basis document | Circular 50/2026/TT-BTC, Circular 18/2026/TT-BTC | Appendix I, Circular 89/2026/TT-BTC |
| Time of application | Before July 1, 2026, or for a tax period prior to July 1, 2026. | From July 1, 2026, for tax periods from July 1, 2026 onwards. |
| Legal basis | Guidance on the Law on Tax Administration under the old framework | Guidance on the Law on Tax Administration in conjunction with Decree 252/2026/ND-CP |
Expert opinion: Common business risks when adopting the 6 replacement tax return forms.
Experts at MAN – Master Accountant Network With over 30 years of experience in tax consulting and auditing in Vietnam, we identify four common risks that businesses and household businesses face when dealing with the conversion of tax forms:
- Risk 1: Using the old template for a new tax period: Many accountants are still accustomed to using pre-saved templates on their computers without checking the version, leading to the submission of outdated forms for tax periods starting from July 1, 2026. Such documents risk being requested for resubmission by the tax authorities, prolonging processing times.
- Risk 2: Confusion between forwarding and new files: With the 2026 year-end tax return, part of the tax period falls before July 1, 2026, while the rest falls after. Without clear separation, businesses can easily apply the wrong tax form to each income segment.
- Risk 3: The tax declaration software has not been updated with the new template: Some domestic accounting software updates its forms later than the effective date of the circular. If accountants do not proactively compare their forms with Appendix I of Circular 89/2026/TT-BTC, the risk of submitting the wrong form can still occur even when using the software.
- Risk 4: The organization filing the tax return on your behalf misses out on updating its records: With forms 01/TCKT and 01/BK-KTHTKD, organizations filing tax returns on behalf of individuals in business partnerships or real estate leasing need to update the new forms for all related clients, not just their own organization's records.
Conclude
The replacement of six tax declaration forms under Circular 89/2026/TT-BTC is a necessary update in the process of reforming tax administrative procedures in Vietnam. While it doesn't change the fundamental nature of tax obligations, the changes to forms and supporting documents still require business households, individual businesses, and organizations filing on behalf of others to proactively review their declaration processes, avoiding waiting until close to the deadline to process their documents.
Tax services at MAN – Master Accountant Network
- Tax accounting services
- Tax consulting services
- Tax settlement services
- Tax reporting services
- VAT refund service
Service contact information at MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network, CPA Vietnam with over 30 years of experience in accounting, auditing, taxation, and corporate financial consulting.
Frequently Asked Questions about the 6 Replacement Tax Forms
From July 1st, 2026, according to Circular 89/2026/TT-BTC, tax return forms for tax periods from this date onwards must use the new format.
The old form should still be used, in accordance with Clause 1, Article 100 of Circular 89/2026/TT-BTC, because the determining point is the tax period, not the date of filing.
No. The symbols and names of the templates remain essentially the same; only the issuing authority and some updated content have been changed according to Appendix I of Circular 89/2026/TT-BTC.
Yes. Forms 01/XSBHĐC and 01/BK-XSBHĐC, applicable to lottery, insurance, and multi-level marketing businesses, are included in the list of 6 tax declaration forms that have been replaced.
Businesses should proactively contact the tax authorities to resubmit their documents using the new form as soon as possible, and at the same time review all related documents to avoid similar errors in subsequent periods. When will the 6 replacement tax return forms be implemented?
Which tax return form should be used for the 2025 tax year, if it is filed after July 1, 2026?
Has the name of Form 01/TKN-CNKD changed when it was implemented under Circular 89/2026/TT-BTC?
Are insurance companies and multi-level marketing businesses required to use the new form?
What happens if I mistakenly submit an outdated form after July 1, 2026?




