Official Document 458/TMĐT-THNV The Decree on E-commerce Tax issued by the Department of E-commerce Tax on September 4, 2026, provides important guidance for individuals and business households operating on online trading platforms. In the context of the booming e-commerce market, mastering the method of provisional personal income tax payment according to Decree 68/2026/ND-CP will help sellers optimize their tax obligations and avoid unnecessary penalties.
Decree 68/2026/ND-CP Along with accompanying guidelines, this marks a significant shift in e-commerce tax management in Vietnam. This article provides a comprehensive analysis from experts to help individuals and business households easily declare and settle taxes accurately and on time.
Summary of key points in Official Letter 458/TMĐT-THNV
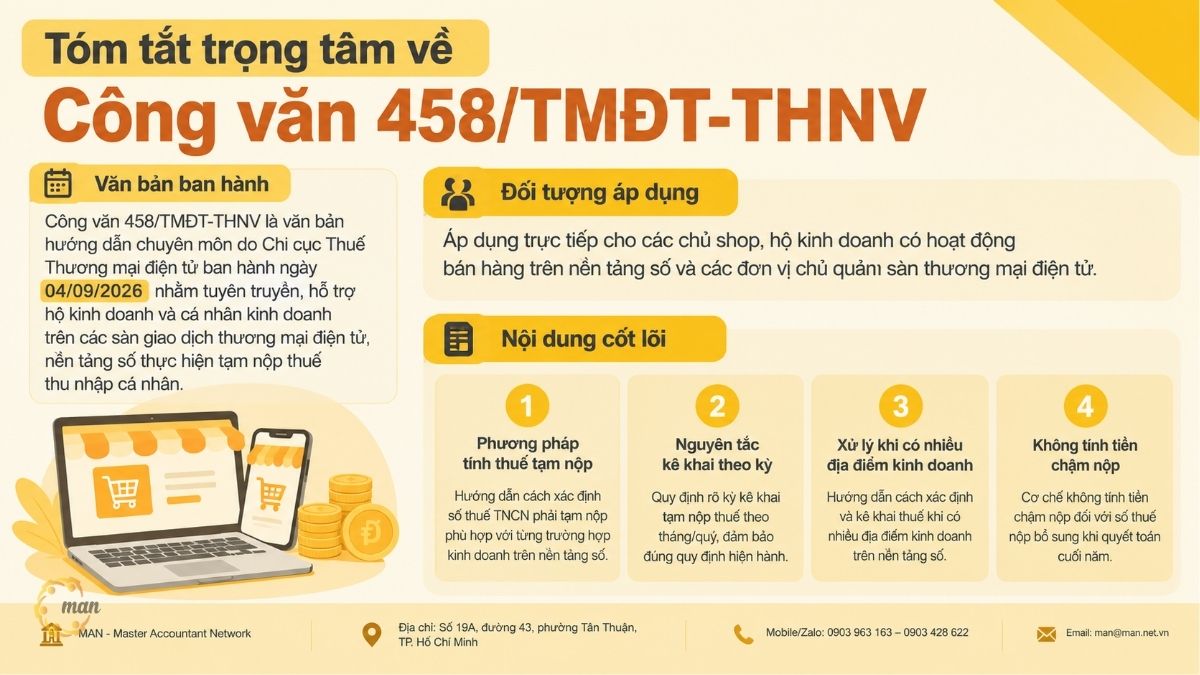
Official Document 458/TMĐT-THNV is a professional guidance document issued by the E-commerce Tax Department on September 4, 2026, aimed at disseminating information and supporting business households and individuals operating on e-commerce platforms and digital platforms in making provisional personal income tax payments.
This document applies directly to shop owners, business households engaged in sales on digital platforms, and e-commerce platform management units. The core content focuses on the method of calculating provisional tax payments, the principle of periodic declaration, handling cases with multiple business locations, and the mechanism for waiving late payment penalties on additional tax payments at the end-of-year settlement.
In what legal context was Official Document 458/TMĐT-THNV issued?
On August 6, 2026, the Ministry of Finance proposed tax support solutions for household businesses, individual businesses, and enterprises. A breakthrough in this proposal is raising the revenue threshold for applying the simplified tax calculation method from VND 3 billion to VND 10 billion.
This content is expected to be included in the draft Law on Support for Small and Medium-Sized Enterprises (amended) to revise the Corporate Income Tax Law and the Personal Income Tax Law, to be submitted to the National Assembly for consideration at the 2nd Session in October 2026.
While awaiting approval from competent authorities for amendments to the regulations, the E-commerce Tax Department issues this document to guide taxpayers in making provisional payments of personal income tax using the simplified method. The legal basis of this document is based on Decree 68/2026/ND-CP and... Decree 252/2026/ND-CP of the Government.
The main function of this guideline is to create consistency between tax authorities, e-commerce platform operators, and taxpayers, helping individual businesses proactively determine their periodic financial obligations.
The role of Official Letter 458/TMĐT-THNV in e-commerce tax management.
Previously, many businesses operating on e-commerce platforms struggled to determine revenue, tax rates, and tax payment locations. The guidance in the new document has thoroughly addressed these issues through three key points:
- Firstly, the formula for calculating provisional tax payments should be made more transparent. Business households will no longer have to worry about complex expense accounting during monthly or quarterly provisional tax payments.
- Secondly, it reduces financial pressure and the risk of late payment penalties. At the end-of-year settlement, if the amount of provisional tax paid is lower than the amount due according to the final settlement, the taxpayer only needs to pay the difference and will not be charged late payment penalties.
- Thirdly, standardize the process of declaring taxes for multiple business locations. The document clearly defines where value-added tax (VAT) is paid and where personal income tax (PIT) is paid, helping businesses with multiple stalls avoid overlapping tax declarations.
Who are the target groups affected by Official Letter 458/TMĐT-THNV?
The entities directly affected by the guidelines in this document include:
- Individuals and household businesses with online stores operating on e-commerce platforms such as Shopee, Lazada, Tiki, and TikTok Shop.
- Individuals and household businesses that provide goods and services on digital platforms and social networks generate revenue.
- Businesses and organizations that own, manage, and operate e-commerce platforms and digital exchanges in Vietnam.
The scope of this document covers tax declaration activities, monthly or quarterly provisional personal income tax payments, value-added tax declaration and payment, tax payment procedures for business locations, and annual personal income tax final settlement procedures.
What are the methods for calculating and the procedures for making provisional payments of personal income tax?
Based on point b, clause 2, Article 10 of Decree No. 68/2026/ND-CP, households and individual businesses subject to personal income tax under the method of taxable income multiplied by tax rate shall declare and make provisional tax payments monthly or quarterly on the same value-added tax return.
The formula for determining the amount of provisional personal income tax payable is specifically stipulated:
|
Provisional personal income tax payment = Taxable revenue of the month or quarter * Tax rate |
In there:
- Taxable revenue: This is the total amount of sales revenue, processing fees, commissions, and service fees generated during the period from the production and business activities of goods and services.
- Tax rates: Applied according to each industry and business sector as stipulated in the tax schedule issued with current law.
The deadlines for filing tax returns and paying taxes strictly adhere to the Tax Administration Law. At the end of the tax year, taxpayers carry out official tax settlement.
What are the regulations for declaring personal income tax and value-added tax when having multiple business locations?
One of the common challenges for e-commerce sellers is having multiple warehouses or business locations situated in different provinces and cities.
According to point b, clause 4, Article 8 of Decree 68/2026/ND-CP, the processing procedure is defined as follows:
- Value Added Tax (VAT): Households and individual businesses declare their revenue and pay VAT at each actual business location where sales activities occur.
- Personal income tax: All personal income tax generated from business locations is centrally paid at the head office.
This regulation helps local tax authorities closely manage value-added tax revenue, while also facilitating taxpayers by consolidating personal income tax into a single point of contact.
What are the procedures for settling personal income tax at the end of the year and handling tax discrepancies?
According to point a, clause 5, Article 10 Decree No. 252/2026/ND-CP, Households and individual business owners who are required to file personal income tax returns must submit their tax return documents no later than the last day of the third month from the end of the tax settlement period.
Handling discrepancies in tax amounts after final settlement:
- In cases where the amount of tax already paid provisionally is lower than the amount of tax payable upon final settlement: The taxpayer must pay the difference. According to point b, clause 2, Article 10 of Decree 68/2026/ND-CP, the taxpayer is not required to pay late payment penalties on this additional tax payment.
- In cases where the amount of tax already paid provisionally is greater than the amount of tax payable upon final settlement: The excess tax paid will be offset against the next period or refunded in accordance with the provisions of Article 12 of Decree 68/2026/ND-CP.
What are the requirements for quarterly tax declarations in 2026 for VAT and personal income tax?
Based on Article 10 of Decree 68/2026/ND-CP (amended and supplemented by Clause 1, Article 1 of Decree 141/2026/ND-CP), the conditions for tax declaration are clearly stipulated based on the scale of revenue:
| Tax Type | Annual revenue limit | Declaration period | Legal basis |
| VAT | 50 billion VND or less | Quarterly | Point a, Clause 1, Article 10 of Decree 68/2026/ND-CP |
| VAT | Over 50 billion VND | By month | Point b, Clause 1, Article 10 of Decree 68/2026/ND-CP |
| Personal Income Tax | Tax Rate * Revenue Method | Declare quarterly (with the same VAT deadline) | Point a, Clause 2, Article 10 of Decree 68/2026/ND-CP |
| Personal Income Tax | Taxable Income * Tax Rate | Monthly/quarterly provisional payment (annual final settlement) | Point b, Clause 2, Article 10 of Decree 68/2026/ND-CP |
Therefore, the revenue threshold of 50 billion VND/year is the criterion for classifying value-added tax (VAT) declaration obligations on a monthly or quarterly basis in 2026. For personal income tax, the declaration deadline will comply with the VAT declaration deadline.
What are the regulations regarding the organization of the accounting system for household businesses?
Compliance with tax laws is closely linked to the organization of accounting work at the business establishment. Article 2 of Circular 152/2025/TT-BTC specifically regulates the arrangement of accounting personnel for business households.
The business representative has the right to keep their own accounting records, appoint an accountant, or hire professional accounting services.
In terms of personnel, the law allows business households to appoint family members as accountants, including: biological father, biological mother, adoptive father, adoptive mother, spouse, biological children, adopted children, and siblings.
Furthermore, household businesses can assign personnel currently holding management, operational, warehousing, or cashier positions, or those frequently involved in buying and selling assets, to also act as accountants. This flexible regulation maximizes opportunities for household businesses to streamline their operational structure.
A comprehensive overview of relevant legal documents requires attention.
To accurately apply the guidelines in Official Letter 458/TMĐT-THNV, taxpayers need to refer to the following comprehensive legal documents:
- Government Decree 68/2026/ND-CP dated March 5, 2026: Provides detailed regulations on tax management for business households and individual businesses.
- Government Decree 141/2026/ND-CP: Amending and supplementing a number of articles of Decree 68/2026/ND-CP on tax declaration periods.
- Government Decree 252/2026/ND-CP: Specifies the deadline for submitting personal income tax final settlement documents.
- Circular 152/2025/TT-BTC of the Ministry of Finance: Guidance on accounting regime for household businesses and individual businesses.
- Official Letter No. 458/TMĐT-THNV dated September 4, 2026, from the E-commerce Tax Department: Guidance on provisional payment of personal income tax on e-commerce platforms.
Real-world case study: Optimizing costs and handling tax obligations for e-commerce businesses.
To better understand the mechanism of provisional tax payment regulations, let's consider the real-life situation of An Phat Household Business, represented by Mr. Nguyen Van A.
Real life situation:
An Phát Household Business operates a fashion business on TikTok Shop and Shopee. Its headquarters are located in District 1, Ho Chi Minh City. In 2026, the household business plans to open an additional warehouse and retail outlet in Bien Hoa City, Dong Nai Province.
- Revenue in 2025: 12 billion VND.
- Actual revenue generated in 2026: VND 18 billion (of which the Dong Nai warehouse contributed VND 5 billion).
- Industry: Retail of clothing (VAT rate: 1%, Personal Income Tax rate: 0.5%).
Analysis and handling:
Regarding the tax filing period: Since the previous year's revenue was below 50 billion VND, An Phát is subject to quarterly VAT tax declaration and provisional personal income tax payment.
Regarding the allocation of tax obligations:
- In Dong Nai: Declare revenue of 5 billion VND and pay VAT (equivalent to 50 million VND) at the tax authority managing the business location in Dong Nai.
- In Ho Chi Minh City (Head Office): Declared total revenue of 18 billion VND. VAT paid on the revenue in Ho Chi Minh City (13 billion * 1% = 130 million VND).
- All quarterly provisional personal income tax payments are submitted to Ho Chi Minh City.
Calculating provisional personal income tax payments for 2026:
- Provisional personal income tax payable for the year = 18 billion * 0.5% = 90 million VND.
When settling accounts at the end of the year:
Let's assume that when settling tax using the income-based method, the total actual personal income tax payable by Mr. A is 105 million VND.
- Additional tax payable = 105 million - 90 million = 15 million VND.
- Based on Official Letter 458/TMĐT-THNV and Decree 68/2026/NĐ-CP, Mr. A paid an additional 15 million VND to the State budget and was not penalized for late payment on this amount.
Results achieved: An Phát business adheres to proper cash flow management, avoiding the risk of late payment penalties and ensuring transparent tax obligations between the two localities.
Expert opinion: Managing e-commerce tax risks in the digital age.
E-commerce in Vietnam is entering a phase of review and tightening of tax management using big data technology. From the perspective of MAN – Master Accountant Network, the issuance of Circular 458/TMĐT-THNV demonstrates the flexibility of the tax sector, creating a safe buffer zone for business households during the policy transition period.
However, consultations have revealed that many businesses are making serious mistakes. The most common is failing to reconcile cash flow between personal bank accounts and revenue reported on e-commerce platforms. Automated verification tools used by tax authorities can easily detect this discrepancy.
Experts at MAN, with 30 years of experience, note that the waiver of late payment penalties for supplementary personal income tax only applies when taxpayers proactively declare and pay the full amount of provisional tax based on actual revenue each period. If a business intentionally conceals its provisional tax revenue, the tax authorities will still collect the outstanding tax and impose administrative penalties along with late payment fees according to the Tax Administration Law during an inspection.
The solution from MAN – Master Accountant Network for shop owners is to establish a standardized accounting system from the outset in accordance with Circular 152/2025/TT-BTC, standardize input invoices, and clearly separate business cash flows. Proactive tax risk management always results in significantly lower costs compared to dealing with issues after an audit.
Conclude
Circular 458/TMĐT-THNV is a practical guidance document that helps individuals and business households on e-commerce platforms master the process of provisional payment and final settlement of personal income tax. Understanding the regulations on tax rates, declaration periods, and the allocation of tax obligations by geographical area not only helps sellers comply with the law but also optimizes their operating cash flow.
Tax services at MAN – Master Accountant Network
- Tax accounting services
- Tax consulting services
- Tax settlement services
- Tax reporting services
- VAT refund service
Service contact information at MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network, CPA Vietnam with over 30 years of experience in accounting, auditing, taxation, and corporate financial consulting.
Frequently Asked Questions about Official Document 458/TMĐT-THNV (FAQ)
Which agency issued Official Document 458/TMĐT-THNV and when did it come into effect?
This document was issued by the E-commerce Tax Department on September 4, 2026, and is immediately applicable to tax declarations for the year 2026.
Will any shortfall in provisional personal income tax payments be subject to late payment penalties upon final settlement?
No. According to the guidelines, if the provisional personal income tax payment is lower than the amount due upon final settlement, the taxpayer must pay the difference and will not be charged late payment penalties.
What revenue level does a business operating on an e-commerce platform need to have to file quarterly tax returns?
Household businesses with annual revenue of 50 billion VND or less are allowed to declare VAT and personal income tax quarterly.
Where should the personal income tax of a household business with multiple warehouses in different provinces be paid?
Value Added Tax (VAT) is paid at each business location, while Personal Income Tax (PIT) is paid centrally at the head office of the business household.
Can e-commerce shop owners do their own accounting?
Yes. The business representative has the right to keep their own accounting records, appoint a family member to act as accountant, or hire external accounting services.