Official document No. 3546/CT-CS dated May 29, 2026, provides important guidance for the forestry business community in implementing value-added tax (VAT) policies. This document is a direct response from the management agency to the difficulties arising in the operation of the plantation timber supply chain, especially in the common preliminary processing stages.
With over 30 years of experience in tax consulting and auditing, the MAN – Master Accountant Network team recognizes this as a necessary legal milestone to synchronize the implementation of the Value Added Tax Law 48/2024/QH15. This article will provide an in-depth analysis of the regulations in this document to help managers accurately understand their rights and obligations.
Summary of key points in Official Letter No. 3546/CT-CS
Official Document No. 3546/CT-CS is a professional guidance document issued by the Tax Department to clarify the VAT policy for newly planted forest timber products that have only undergone basic processing. The document applies to businesses, cooperatives, and cooperative unions that pay tax using the deduction method when buying and selling timber products at the commercial stage.
The regulations stipulate that these transactions are not subject to VAT declaration and payment. This helps timber businesses eliminate the risk of tax rate discrepancies and optimize cash flow management processes.
Legal basis and validity of Official Letter No. 3546/CT-CS
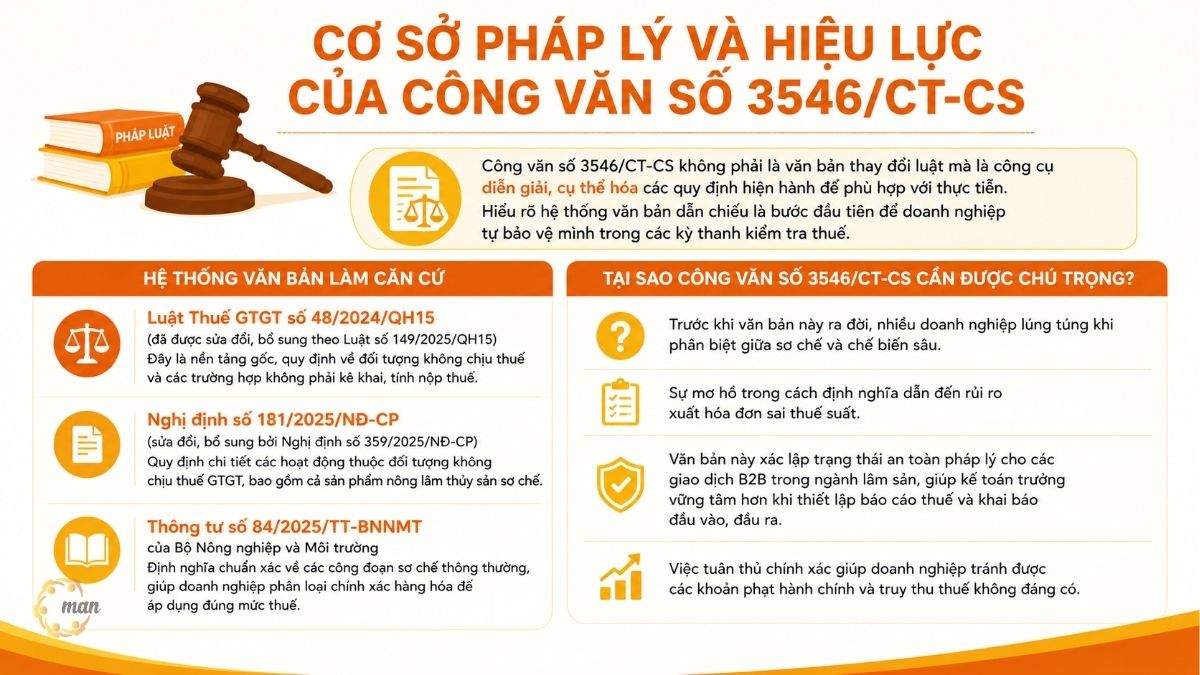
Official document No. 3546/CT-CS This is not a document that amends the law, but rather a tool for interpreting and specifying existing regulations to suit practical realities. Understanding the system of referenced documents is the first step for businesses to protect themselves during tax audits.
The system of documents serving as a basis
Experts at MAN – Master Accountant Network note that the legal validity of this document is based on a combination of the latest Laws, Decrees, and Circulars:
- VAT Law No. 48/2024/QH15 (amended and supplemented by Law No. 149/2025/QH15): This is the fundamental basis, stipulating the subjects not subject to tax and cases where tax declaration, calculation, and payment are not required.
- Decree No. 181/2025/ND-CP (Amended and supplemented by Decree No. 359/2025/ND-CP): Specifies detailed regulations on activities exempt from Value Added Tax (VAT), including semi-processed agricultural, forestry, and aquatic products.
- Circular No. 84/2025/TT-BNNMT From the Ministry of Agriculture and Environment: Precisely defining common preliminary processing stages helps businesses accurately classify goods to apply the correct tax rates.
Why does Official Document No. 3546/CT-CS need to be given attention?
Prior to this document, many businesses struggled to distinguish between preliminary processing and further processing. This ambiguity in definition led to the risk of issuing invoices with incorrect tax rates. This document establishes legal security for B2B transactions in the forestry industry, giving chief accountants more confidence when preparing tax reports and declaring inputs and outputs. Accurate compliance helps businesses avoid unnecessary administrative penalties and tax arrears.
See more articles at: What is the tax rate for wood, wood pellets, wood chips, and other wood products?
Analysis of VAT regulations for ordinary semi-processed timber according to Official Letter No. 3546/CT-CS
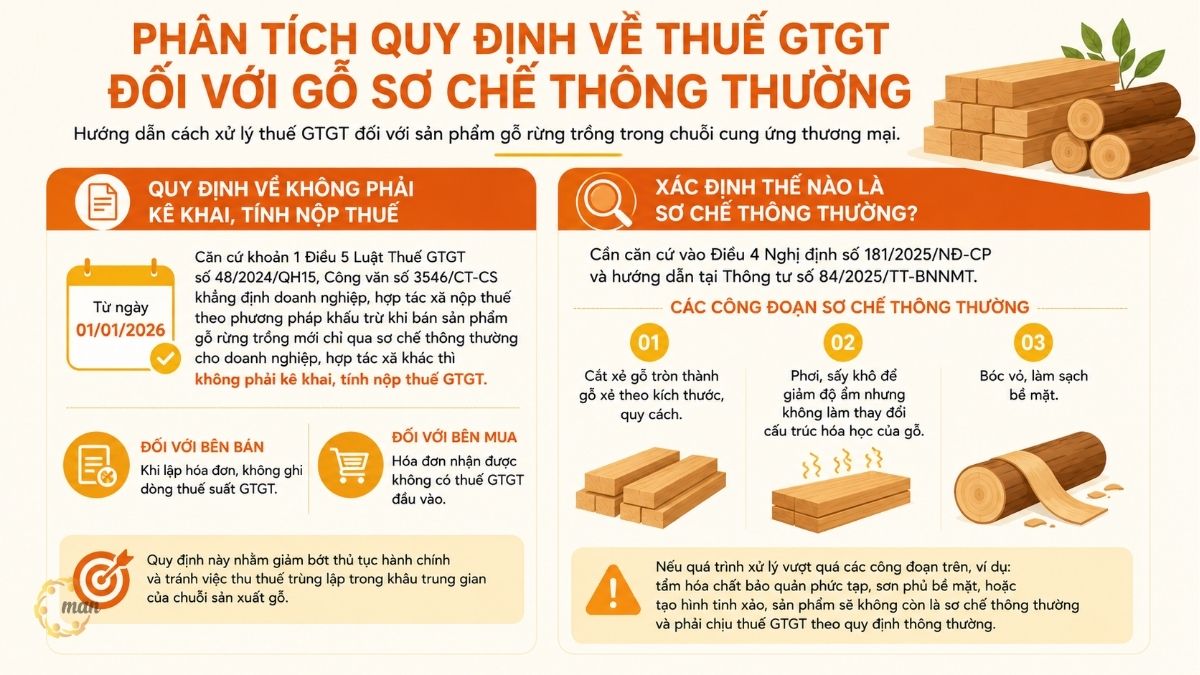
The central content of the guidance document is on how to handle taxes on plantation timber products within the commercial supply chain. This is a crucial step affecting the cash flow of both the seller and the buyer.
Regulations regarding exemption from tax declaration and payment.
Based on Clause 1, Article 5 of the Value Added Tax Law No. 48/2024/QH15, Official Letter No. 3546/CT-CS affirms that: from January 1, 2026, enterprises and cooperatives paying tax using the deduction method when selling newly processed plantation timber products to other enterprises and cooperatives are not required to declare or calculate and pay tax. VAT.
This means that when issuing invoices, the selling business will not include the VAT rate. For the buyer, the invoice received will also not have this information. input VAT. This regulation aims to reduce administrative procedures and avoid double taxation in the intermediate stages of the wood production chain.
What constitutes standard pre-processing?
The classification of wood products as either semi-processed or processed is complex and often controversial. According to experts from MAN, businesses need to refer to Article 4 of Decree No. 181/2025/ND-CP and the guidelines in Circular No. 84/2025/TT-BNNMT.
Typically, wood processing includes basic steps such as:
- Round logs are cut and sawn into lumber according to specifications.
- Drying or air-drying reduces moisture content but does not alter the chemical structure of the wood.
- Peel the skin and clean the surface.
If the processing goes beyond the above steps, such as applying complex chemical preservatives, surface coating, or intricate shaping, the product will no longer be considered a normal pre-processed product and will be subject to VAT according to standard regulations.
See more articles: Is acacia wood subject to VAT? Detailed guidance is provided in Official Letter 4968/CT-CS.
Scope and conditions for application of Official Letter No. 3546/CT-CS
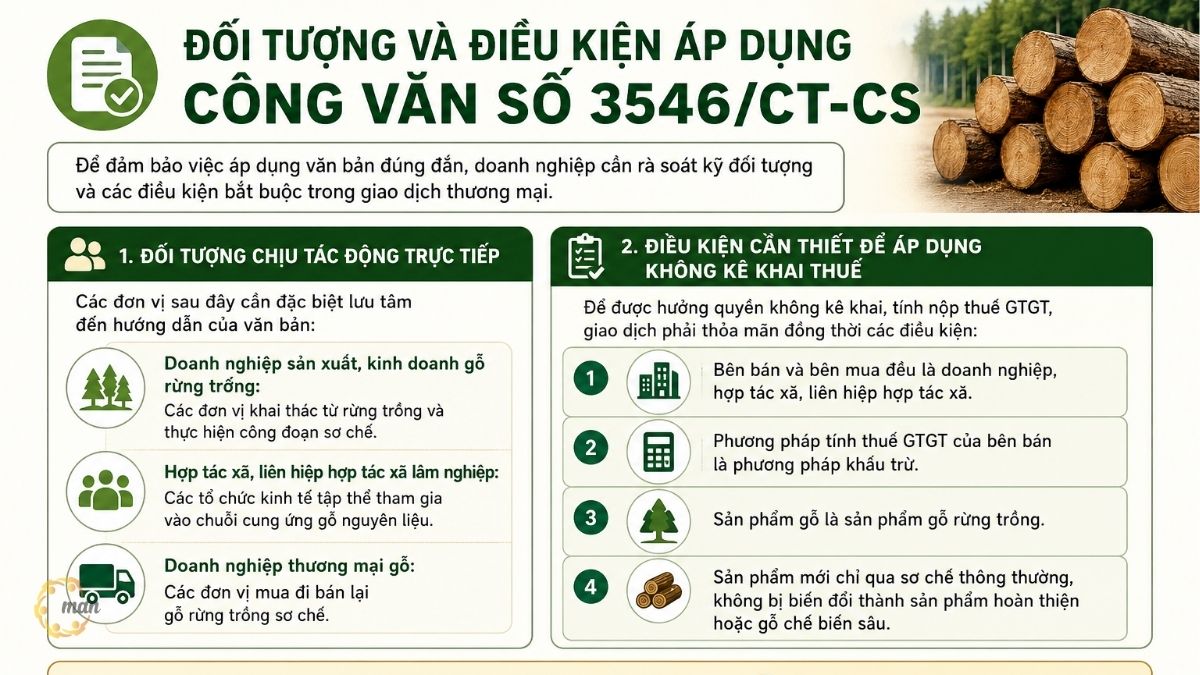
To ensure proper application of the regulations, businesses need to carefully review the subjects and mandatory conditions in commercial transactions.
Those directly affected
The following units should pay particular attention to the instructions in this document:
- Businesses involved in the production and trading of timber from planted forests: Units that harvest timber from planted forests and carry out preliminary processing.
- Forestry cooperatives and cooperative unions: Collective economic organizations participating in the raw timber supply chain.
- Timber trading businesses: Units that buy and resell timber from plantations for preliminary processing.
The necessary conditions for applying for tax exemption are as follows:
To be eligible for exemption from VAT declaration and payment, the transaction must simultaneously satisfy the following conditions:
- Both the seller and the buyer are businesses, cooperatives, or cooperative unions.
- The seller's method for calculating VAT is the deduction method.
- The wood products are made from wood sourced from plantations.
- The product has only undergone basic processing and has not been transformed into a finished product or deeply processed wood.
If a business sells semi-processed timber to household businesses or individuals, the regulation regarding non-declaration of tax will not apply similarly. Therefore, verifying the legal status of the partner is a mandatory risk control step.
Tax risk management in the forestry industry from a MAN perspective.
With over 30 years of consulting experience, experts at MAN – Master Accountant Network have identified many potential risks that timber businesses often overlook when implementing Circular No. 3546/CT-CS.
Common accounting risks
- Misclassification of products: Businesses arbitrarily classify products as semi-processed when in reality they have undergone complex processing. This leads to the inability to issue VAT invoices, resulting in tax evasion during inspections by authorities.
- Invalid invoice: An invoice issued incorrectly regarding the tax rate for cases not falling under the category of normal preliminary processing.
- Poor documentation: Lack of records proving the origin of plantation forests or processing procedures makes it difficult for tax authorities to determine the validity of transactions.
The optimal solution from MAN
To minimize risks, businesses need to implement the following management solutions:
- Establish a rigorous document archiving process: Maintain complete records of invoices, contracts, shipping documents, and technical documentation proving the product is semi-processed wood.
- Review the product list: Periodically review the product list to ensure it conforms to the definition in Circular No. 84/2025/TT-BNNMT.
- Training accounting staff: Regularly update the accounting department on new regulations such as Official Letter No. 3546/CT-CS to avoid errors in invoice preparation.
Case Study: Practical Application in a Wood Manufacturing Company
To clarify further, we present a hypothetical scenario based on a consultation conducted by MAN – Master Accountant Network at a business in Binh Duong province.
Business situation
Company A operates in the timber business. They purchase logs from a forestry cooperative (already debarked and cut into sections). Company A then further processes the logs into sawn timber according to the dimensions required by their customer, Company B. Both companies pay taxes using the deduction method.
Analysis and processing according to Official Letter No. 3546/CT-CS
- According to Decree No. 181/2025/ND-CP, the wood products of Company A, after sawing, are still considered ordinary semi-processed wood.
- According to the guidelines in Official Letter No. 3546/CT-CS, when Company A sells to Company B, Company A is not required to declare and pay VAT on the invoice.
- Company A only needs to clearly state on the invoice that the product is ordinary processed plantation timber, which is not subject to tax or not subject to VAT declaration.
Lessons learned
Understanding Circular No. 3546/CT-CS helps Company A avoid overpaying output VAT, while also assisting Company B in accurately accounting for input costs. If Company A does not fully understand the regulations and proactively issues invoices with incorrect tax rates, they will cause unnecessary confusion for their partners and increase administrative costs.
Comparison table of regulations related to Official Letter No. 3546/CT-CS
For your convenience, we have compiled the core documents related to tax policies on semi-processed timber in the table below.
| Document | Main content | Impact on business |
| VAT Law 48/2024/QH15 | Regulations regarding subjects not subject to tax and not required to declare tax. | Establishing the highest legal foundation for future guidelines. |
| Decree 181/2025/ND-CP | Details of common pre-processing cases | Helps to classify goods accurately. |
| Circular 84/2025/TT-BNNMT | Technical definition of preliminary processing in forestry. | The basis for providing explanations to the tax authorities during an audit. |
| Official Document 3546/CT-CS | Specific instructions on not declaring VAT. | Tools for direct implementation at the commercial stage. |
Conclude
Official document No. 3546/CT-CS is a necessary document that helps resolve administrative procedural difficulties for businesses in the wood industry. Understanding and correctly applying its contents will not only help businesses comply with the law but also optimize costs and manage cash flow effectively.
At MAN – Master Accountant Network, we understand the challenges Vietnamese businesses face in managing tax risks. With a team of experts boasting over 30 years of practical experience, we provide comprehensive solutions. tax settlement services, tax accounting services, tax reporting services and in-depth tax consulting. If your business is facing difficulties with tax policies or needs a reliable partner to work with, contact MAN for advice on the best solutions for your business operations.
Service contact information at MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network, CPA Vietnam with over 30 years of experience in accounting, auditing, taxation, and corporate financial consulting.
MAN – Master Accountant Network is committed to providing transparent, up-to-date professional information in accordance with current legal regulations and adhering to professional standards in the fields of accounting, auditing, and taxation.
Frequently Asked Questions about Official Letter No. 3546/CT-CS
No. This document only applies to transactions between businesses, cooperatives, and cooperative unions. Transactions with household businesses or individuals must still be conducted according to the usual VAT regulations.
Yes, drying is a common preliminary processing step stipulated in Decree No. 181/2025/ND-CP. However, if after drying further processing steps such as artistic shaping or complex chemical bonding are required, a reassessment is necessary according to the guidelines of the Ministry of Agriculture and Environment.
If you have declared VAT for eligible transactions that were not declared, you need to file a supplementary declaration to adjust your revenue and output tax downwards. Experts at MAN recommend that businesses review their tax returns from previous periods to proactively address any issues before tax authorities conduct an audit.
This document serves as guidance on the application of current legal texts. Its validity is tied to the laws and decrees it refers to. Therefore, as long as the aforementioned legal documents remain in effect, Circular No. 3546/CT-CS remains a valid and enforceable guideline.
Absolutely. The team of experts at MAN - Master Accountant Network, with 30 years of experience, is always ready to assist businesses in reviewing documentation, classifying products, and building documentation processes to ensure businesses are always prepared for tax audits. If I sell semi-processed timber to household businesses, do I need to apply Circular No. 3546/CT-CS?
Are kiln-dried wood products considered to be undergoing normal processing?
What should I do if I have already declared VAT for these transactions in the past?
Does Official Document No. 3546/CT-CS have an expiration date?
Does MAN assist businesses in verifying the documentation for processed timber?