

Guidelines for determining night shift pay exceeding 30% and overtime pay exceeding 40 hours/month, 300 hours/year when calculating personal income tax. This is a core task requiring absolute accuracy from the accounting and human resources departments in businesses. Precisely distinguishing between tax-exempt and taxable income is a crucial legal boundary between optimizing legitimate expenses and the risk of tax audits and administrative penalties during tax settlement.
As prescribed in Labor Code 2019, Decree 145/2020/ND-CP, Decree 253/2026/ND-CP In line with the latest professional guidance in Official Letter 10311/NBI-QLDN1 dated August 7, 2026, from the Ninh Binh Provincial Tax Department, tax incentives for night shift and overtime pay are directly linked to the working time ceiling. This in-depth article from MAN – Master Accountant Network will comprehensively analyze the regulations, calculation methods, and tax risk management solutions for businesses.
Summary of key points regarding the determination of night shift pay exceeding 30% and overtime pay exceeding 40 hours/month, 300 hours/year when calculating personal income tax.
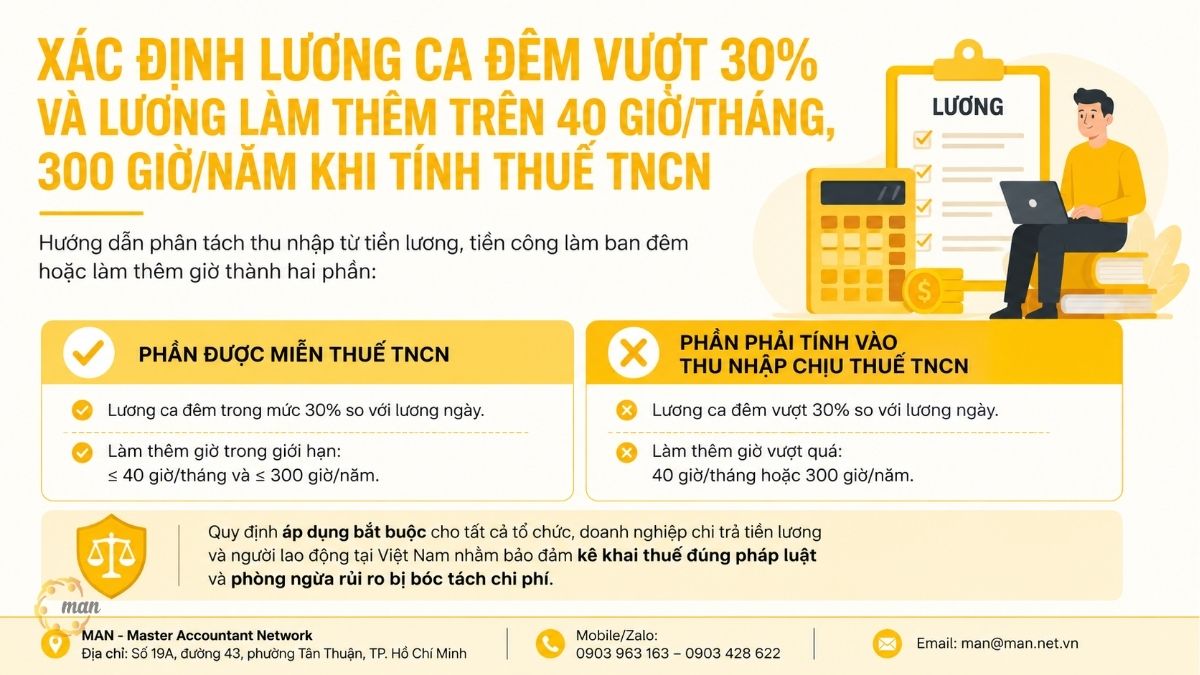
- The guidelines for determining night shift wages exceeding 30% and overtime wages exceeding 40 hours/month or 300 hours/year for personal income tax calculation involve separating income from night shift or overtime work into two parts: the portion exempt from personal income tax (within the limits of labor law) and the portion subject to personal income tax (the portion exceeding the prescribed limit or time ceiling).
- This regulation is mandatory for all organizations and businesses paying salaries and employees in Vietnam to ensure proper tax declarations and prevent the risk of expense discrepancies.
Guidelines for determining night shift pay exceeding 30% and overtime pay exceeding 40 hours/month, 300 hours/year when calculating personal income tax according to current law.
Determining whether night shift and overtime pay is subject to or exempt from personal income tax is based directly on the principle that only overtime and night shift income that meets the conditions and time limits stipulated by labor law is eligible for tax exemption. All wages paid at rates higher than the stipulated level or for overtime exceeding the permitted labor limit are considered taxable income. personal income tax of the individual worker.
How is personal income tax calculated for night shift wages exceeding the 30% limit?
Based on Clauses 2 and 3 of Article 98 of the 2019 Labor Code, which regulate the payment of wages for night work and overtime work at night:
- Workers who work at night are entitled to additional pay of at least 30%, calculated based on the hourly wage rate or the actual wage paid for the work performed during a normal workday.
- Workers who work overtime at night, in addition to their daytime and nighttime overtime pay, are also entitled to an extra 20% salary calculated based on the hourly wage rate or the salary for the work performed during the day on a normal workday, a weekly rest day, or a public holiday.
According to the principle of preferential personal income tax as stipulated in Article 26. Decree 253/2026/ND-CP and detailed instructions can be found in Official Letter 10311/NBI-QLDN1 from the Ninh Binh Provincial Tax Department:
- Salaries and wages for night work that comply with labor laws are exempt from personal income tax when paid.
- If a business pays employees for night work using the 35% wage rate as the basis for calculation according to regulations, then the portion of the wage corresponding to the 30% rate (determined according to Article 56 of Decree 145/2020/ND-CP) is exempt from personal income tax.
- The portion of the employee's salary paid in excess of the amount stipulated by labor law (in this case, the difference between 5% and 30%) must be included in the employee's taxable personal income.
How is personal income tax handled for overtime pay exceeding 40 hours/month or 300 hours/year?
Based on Article 107 of the 2019 Labor Code, overtime hours must strictly adhere to the following limits: Not exceeding 50 hours of normal working hours in one day; in cases where working hours are based on a weekly schedule, the total number of normal working hours and overtime hours must not exceed 12 hours in one day; not exceeding 40 hours in one month and not exceeding 200 hours in one year (except in special cases where overtime can reach up to 300 hours in one year as stipulated in Clause 3, Article 107).
Based on Clauses 1 and 3 of Article 26 of Decree 253/2026/ND-CP and the guidance provided below. Official document 10311/NBI-QLDN1, Overtime pay for employees is broken down into four specific cases as follows:
- Case 1 (Exceeding the monthly ceiling): If an employee works overtime exceeding 40 hours in a month, the portion of their salary or wages corresponding to those overtime hours is not exempt from personal income tax and must be included in their taxable income for the month in which it was earned.
- Case 2 (Exceeding the annual ceiling): If an employee has not exceeded 40 overtime hours in a month, but the total cumulative overtime hours for the year have reached the limit of 300 hours/year (for businesses subject to the 300-hour limit), then the portion of salary or wages corresponding to the overtime hours exceeding the 300-hour limit is not exempt from personal income tax.
- Case 3 (Exceeded by month but not by year): If an employee works overtime exceeding 40 hours per month, but the total overtime hours for the year do not exceed 300 hours per year, the salary or wages corresponding to the excess hours (over 40 hours per month) are not exempt from personal income tax.
- Case 4 (Simultaneous violation of two ceilings): If an employee simultaneously exceeds both the 40-hour/month limit and the 300-hour/year limit, their taxable income will be determined based on the actual overtime hours worked from the point where they no longer meet either of the limits stipulated by labor law.
Legal regulations on guaranteeing wages and workers' right to work.
Besides the personal income tax exemption policy, the basis for determining the validity of night shift and overtime pay expenses must be based on compliance with the core principles of the 2019 Labor Code.
How must businesses ensure they pay their employees' wages?
Based on Article 90 of the 2019 Labor Code regarding wages:
- Wages are the amount of money that an employer pays to an employee according to an agreement for performing work, including the salary based on the job or position, salary allowances, and other additional payments.
- Salaries for specific jobs or positions must not be lower than the minimum wage set by the Government.
- Employers must ensure equal pay, without discrimination based on gender, for workers performing work of equal value.
Therefore, night shift or overtime pay, regardless of the form, must be based on transparent agreements, comply with minimum wage levels, and ensure gender equality within the enterprise.
How are workers' rights currently regulated?
Based on Article 10 of the 2019 Labor Code, which stipulates the right to work of employees:
- The right to choose one's employment, to work for any employer and in any place that is not prohibited by law.
- Contact employers directly or through employment service organizations to find jobs that match your aspirations, abilities, professional qualifications, and health.
Overtime or night shift work must be entirely voluntary and agreed upon by the workers; coercion or violation of the right to work freely as stipulated by law is prohibited.
Compilation of a list of applicable current legal documents.
To help accountants and HR departments quickly find information, experts at MAN – Master Accountant Network have systematized the legal documents that form the basis for determining personal income tax and labor obligations:
| Document number | Issuing authority | Date of issuance | Revised summary |
| Labor Code 2019 (Law No. 45/2019/QH14) | National Assembly | 20/11/2019 | Regulations on the right to work (Article 10), principles of wage payment (Article 90), payment for night shifts and overtime (Article 98), overtime limit of 40 hours/month, 200-300 hours/year (Article 107). |
| Decree 145/2020/ND-CP | Government | 14/12/2020 | Detailed guidance on the implementation of the Labor Code regarding working conditions, night work wages, and overtime pay (Article 56). |
| Decree 253/2026/ND-CP | Government | 2026 | Detailed regulations on personal income tax exemption for night shift wages, overtime pay, and wages for unused vacation days (Article 26). |
| Official document 10311/NBI-QLDN1 | Ninh Binh Provincial Tax | 07/08/2026 | This guide specifies the rules for allocating and separating taxable income for personal income tax purposes, specifically for night shift wages exceeding 30% and overtime wages exceeding the 40 hours/month and 300 hours/year limits. |
The role of accurately determining night shift and overtime pay costs in tax risk management.
From MAN's perspective, personnel costs and salaries are always among the most thoroughly scrutinized indicators when tax authorities conduct audits and tax settlements at businesses.
Accurately determining the tax-exempt portion of night shift and overtime pay offers practical benefits:
- Protecting the legitimate financial rights of workers: Ensure that employees receive the correct portion of their income that is exempt from personal income tax, in accordance with the State's incentive policy for high-intensity workers.
- Preventing the risk of tax arrears and penalties for tax violations: Incorrectly declaring tax exemptions for overtime hours exceeding the limit will result in the tax authorities investigating and collecting the underdeclared personal income tax, calculating a late payment penalty of 0.031 TP3T/day, and imposing administrative penalties of 1 to 2 times the amount of underdeclared tax.
- Standardize labor legal records and deductible expenses: This helps businesses protect payroll expenses when calculating corporate income tax, while maintaining consistent compliance between tax reporting and human resource management.
Conditions and subjects to which the 300-hour/year overtime limit applies
The law stipulates that the maximum overtime hours is typically 200 hours per year. Applying an overtime limit exceeding 200 hours to 300 hours per year requires businesses to belong to the correct category and to have completed all necessary administrative procedures.
Those permitted to organize overtime work are those with more than 200 hours but less than 300 hours per year.
According to Clause 3, Article 107 of the 2019 Labor Code, employers are only allowed to have employees work overtime for no more than 300 hours per year in the following cases:
- Manufacturing and processing for export of textile, garment, leather, footwear, electrical, electronic, agricultural, forestry, salt, and aquatic products.
- Electricity production and supply, telecommunications, oil refining; water supply and drainage.
- Addressing tasks that require highly skilled and technical labor, which the labor market cannot adequately or promptly supply.
- Addressing urgent tasks that cannot be postponed due to the seasonal nature or timing of raw materials or products, or to resolve issues arising from unforeseen objective factors such as weather, natural disasters, fires, enemy attacks, power outages, raw material shortages, or technical failures in the production line.
- Other cases are as stipulated by the Government.
Mandatory procedures and conditions for 300 hours of overtime pay to be exempt from personal income tax.
Experts at MAN, with 30 years of experience, note that, regardless of whether the business is in the electronics or textile industry, if it lacks the following procedural conditions, the tax authorities have full grounds to revoke the personal income tax exemption for overtime hours from 201 to 300:
- Overtime notice: It is mandatory to send a written notification to the specialized labor agency under the Provincial People's Committee (Department of Labor, War Invalids and Social Affairs) as stipulated in Clause 4, Article 107 of the 2019 Labor Code.
- Employee's written consent: There is a written agreement clearly stating the employee's consent regarding the time, location, and content of overtime work.
- Timekeeping and payment documents: There are detailed time sheets separating day and night shifts, overtime pay sheets with signed confirmations, and internal spending regulations/collective labor agreements clearly specifying the overtime pay rates.
Practical Case Study: Personal Income Tax Analysis for Electronics Factory Workers
To help businesses clearly visualize the cost breakdown process, let's look at a real-world case study handled by MAN's team of experts at an electronics component manufacturing company.
Situational context
K Electronics Manufacturing Co., Ltd. (operating in the electronics industry, subject to an overtime limit of 300 hours/year). In October 2026, worker Nguyen Van A had the following work performance data:
- Normal daytime wage: 60,000 VND/hour.
- The company's night shift allowance is 135% of daily wage (5% higher than the minimum 30% stipulated by the Labor Law). Total night shift hours in the month: 80 hours.
- Daytime overtime hours in October 2026: 45 hours (exceeding the 40-hour/month limit by 5 hours).
- Overtime pay during the day: Paid at the daily wage rate of 150% (90,000 VND/hour).
- As of the end of September 2026, Mr. A's cumulative overtime hours from the beginning of the year totaled 290 hours.
Analyze and break down personal income tax obligations for each type of income.
The team of experts from MAN carried out the allocation of Mr. A's salary stream for October 2026 in accordance with the guidelines in Official Letter 10311/NBI-QLDN1:
Allocation of night shift wages (80 hours)
- Actual hourly rate: 60,000 x 135% = 81,000 VND/hour. This includes a base salary of 60,000 VND and a night shift allowance of 21,000 VND/hour (35%).
- Tax-exempt portion of personal income tax: Night shift allowance (30%) as stipulated by labor law. Tax-exempt amount = 80 hours x (60,000 x 30%) = 80 x 18,000 = 1,440,000 VND.
- The portion to be included in taxable personal income: The portion of the night shift allowance exceeding the regulations (80 hours x 3,000 = 240,000 VND) plus the entire portion of the basic daytime salary (80 hours x 60,000 = 4,800,000 VND).
Allocation of overtime pay for daytime work (45 hours)
The total number of overtime hours in the month is 45 hours. The monthly ceiling is 40 hours. The cumulative hours at the beginning of the month are 290 hours, leaving only 10 hours (300 – 290) remaining at the annual ceiling. These 45 hours are divided into 3 intervals:
- Approximately 1 (first 10 hours): The monthly limit (10 hours < 40 hours) and the annual limit (290 hours + 10 hours = 300 hours) have not been exceeded. The difference in overtime pay (90,000 - 60,000 = 30,000 VND/hour) is exempt from personal income tax. Total tax-exempt amount = 10 hours x 30,000 = 300,000 VND. The base salary (600,000 VND) is subject to tax.
- Approximately 2 (the next 30 hours, from hour 11 to hour 40): Although the monthly limit (40 hours) has not been exceeded, the annual limit has been surpassed (reaching between 301 and 330 hours). Because the annual limit has been violated, the entire salary for these 30 hours (30 hours x 90,000 = 2,700,000 VND) is not exempt from personal income tax.
- Approximately 3 (the last 5 hours, from hour 41 to hour 45): Exceeding both the monthly limit (40 hours) and the annual limit means the entire salary for these 5 hours (5 hours x 90,000 = 450,000 VND) is not exempt from personal income tax.
| Income generated | Number of hours | Payment rate (VNĐ/hour) | Total income received (VND) | Tax-Exempt Income (VND) | Taxable income for personal income tax (VND) |
| Night shift allowance (35%) | 80 hours | 21.000 | 1.680.000 | 1,440,000 (level 30%) | 240,000 (level 5% exceeded) |
| Working the first 10 hours overtime (Legally) | 10 o'clock | 90.000 | 900.000 | 300,000 (difference from 50%) | 600,000 (original part 100%) |
| Work an additional 30 hours (Exceeding the annual limit) | 30 hours | 90.000 | 2.700.000 | 0 | 2,700,000 (entire 150%) |
| Worked an extra 5 hours at the end (exceeded both work limits) | 5 o'clock | 90.000 | 450.000 | 0 | 450,000 (entire 150%) |
Through consultation and support in recreating the detailed allocation table from MAN – Master Accountant Network, K Electronics Manufacturing Co., Ltd. completely eliminated the risk of being subject to back taxes on personal income tax and late payment penalties during the subsequent tax audit.
Comparison table of cases violating overtime limit and personal income tax treatment.
The summary table below helps the accounting department easily classify and apply the correct tax rules to each actual case that arises:
| Overtime situation | Assessing compliance with the Labor Code | Principles for determining income exempt from personal income tax. | Principles for determining taxable personal income. |
| Monthly <= 40 hours; Annually <= 300 hours | In accordance with the law. | The difference between overtime pay and regular daily pay is tax-exempt. | Calculate the tax on the portion of wages corresponding to the normal daytime rate (100%). |
| Month > 40 hours; Year <= 300 hours | Violation of the monthly overtime limit. | Only the difference in hours used (less than or equal to 40 hours) in a month is exempt from tax. | Tax the full salary (both base salary and any additional pay) for hours exceeding 40 hours per month. |
| Monthly <= 40 hours; Annually > 300 hours | Violation of the overtime limit for one year. | No tax exemption is granted for any overtime hours after exceeding the 300-hour/year limit. | Tax is calculated on all wages paid for overtime hours earned after reaching the 300-hour mark. |
| Month > 40 hours; Year > 300 hours | Violation of two ceilings simultaneously. | All overtime pay earned during this period is not tax-exempt. | Tax (100%) will be calculated on the entire amount of actual overtime pay earned from the time of the violation. |
MAN expert analysis: Real risks and strategies for managing payroll tax costs.
Solving payroll tax problems is not just about simple algebraic calculations; it requires a comprehensive risk management perspective. With over 30 years of experience, MAN's team of experts has identified three of the most common mistakes that lead to heavy penalties for businesses in Vietnam:
- Combining night shift allowances into the fixed salary without separating them on the payroll: Many businesses agree on a fixed salary that includes night shift allowances but do not separate the unit price from the actual working hours. During an audit, the tax authorities will reject all tax exemptions and calculate personal income tax on the total income.
- Missing procedure: Notification of 300 hours of overtime work submitted to the Department of Labor, War Invalids and Social Affairs. This is a common administrative error made by many businesses. Whether in the textile or electronics industry, if they fail to submit the notification as required by Clause 4, Article 107 of the 2019 Labor Code, all overtime hours from the 201st to the 300th hour will be considered illegal and excluded from the personal income tax exemption.
- Claim tax exemption for both the original daytime salary and overtime pay: Accountants often mistakenly believe that all overtime pay (150%, 200%, 300%) is tax-exempt. In reality, the law only exempts the higher portion (50%, 100%, 200%), while the basic salary (100%) is still subject to normal personal income tax.
Businesses need to establish automated internal control processes that provide real-time alerts when workers reach 35 overtime hours per month or 180 overtime hours per year. Reviewing labor contracts, financial regulations, and standardizing reporting documents from the beginning of the year is a key solution to help businesses optimize tax costs in Vietnam in the safest way.
Conclude
Adhering to the guidelines for determining night shift pay exceeding 30% and overtime pay exceeding 40 hours/month and 300 hours/year when calculating personal income tax plays a crucial role in ensuring businesses strictly comply with tax laws, avoiding the risk of financial recovery, and protecting the legitimate rights of employees. The close connection between the Labor Code and tax policies requires accounting and human resources personnel to thoroughly understand the nature of the regulations to process documents transparently.
Tax services at MAN – Master Accountant Network
- Tax accounting services
- Tax consulting services
- Tax settlement services
- Tax reporting services
- VAT refund service
Service contact information at MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network, CPA Vietnam with over 30 years of experience in accounting, auditing, taxation, and corporate financial consulting.
Frequently Asked Questions about determining night shift pay exceeding 30% and overtime pay exceeding 40 hours/month, 300 hours/year when calculating personal income tax (FAQ)
If a company pays a night shift allowance (code 40%), how is the personal income tax portion determined?
The night shift allowance (30%) is in accordance with labor law regulations and is exempt from personal income tax. The excess amount (40% - 30%) paid by the employer must be added directly to the employee's taxable income for the month in which it is paid.
If an employee works 45 overtime hours in a month but only works 100 hours in a year, are the 5 overtime hours tax-exempt?
No. 5 hours of overtime exceeding the 40-hour/month limit is considered a violation of the monthly overtime limit. The wages paid for these 5 excess hours must be included in taxable personal income.
If a company fails to notify the Department of Labor about the 300 overtime hours, how will the hours between 201 and 300 be handled?
Due to not meeting the mandatory administrative procedures in Clause 4, Article 107 of the 2019 Labor Code, overtime hours ranging from 201 to 300 are considered a violation of labor law, and the entire salary for these hours is not eligible for personal income tax exemption.
Is the portion of overtime pay calculated at the normal daytime rate exempt from personal income tax?
No. Tax law stipulates that only the excess salary (the difference exceeding the normal daily wage) is exempt from personal income tax. The base salary (100%) is still subject to personal income tax.
Are businesses operating in the trade and service sector allowed to apply a 300-hour/year overtime limit?
No. Ordinary service trade is not included in the list of specific industries, occupations, and jobs to which the 300-hour/year ceiling applies according to Clause 3, Article 107 of the 2019 Labor Code. The maximum applicable ceiling is 200 hours/year.




