

10 new points of Decree 253/2026/ND-CP The recently issued regulation marks a significant turning point in the management of personal income tax in Vietnam. This document brings about many positive changes regarding tax exemption thresholds, family allowance deductions, and regulations on taxable income, and officially takes effect from July 1, 2026.
For businesses and employees, staying up-to-date on these changes not only optimizes tax obligations but also provides an opportunity to enhance internal benefits. This article from the MAN – Master Accountant Network expert team will analyze in detail 10 core new points along with the best risk management solutions for the 2026 tax year.
Summary of the 10 key new points of Decree 253/2026/ND-CP
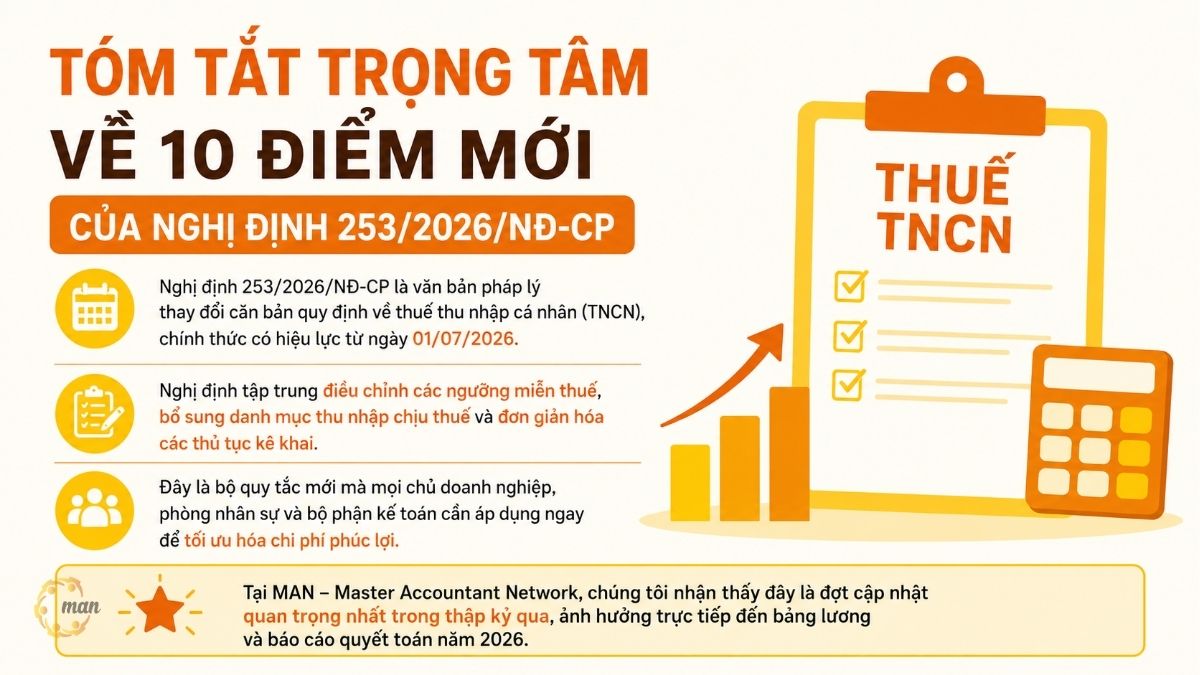
Decree 253/2026/ND-CP It is a legal document that fundamentally changes the regulations regarding personal income tax (PIT), Officially effective from July 1, 2026, the Decree focuses on adjusting tax exemption thresholds, supplementing the list of taxable income, and simplifying declaration procedures.
This is a new set of guidelines that every business owner, HR department, and accounting department needs to implement immediately to optimize employee benefits costs. At MAN – Master Accountant Network, we see this as the most important update in the past decade, directly impacting payroll and financial reporting in 2026.
Details of 10 new points in Decree 253/2026/ND-CP on personal income tax.
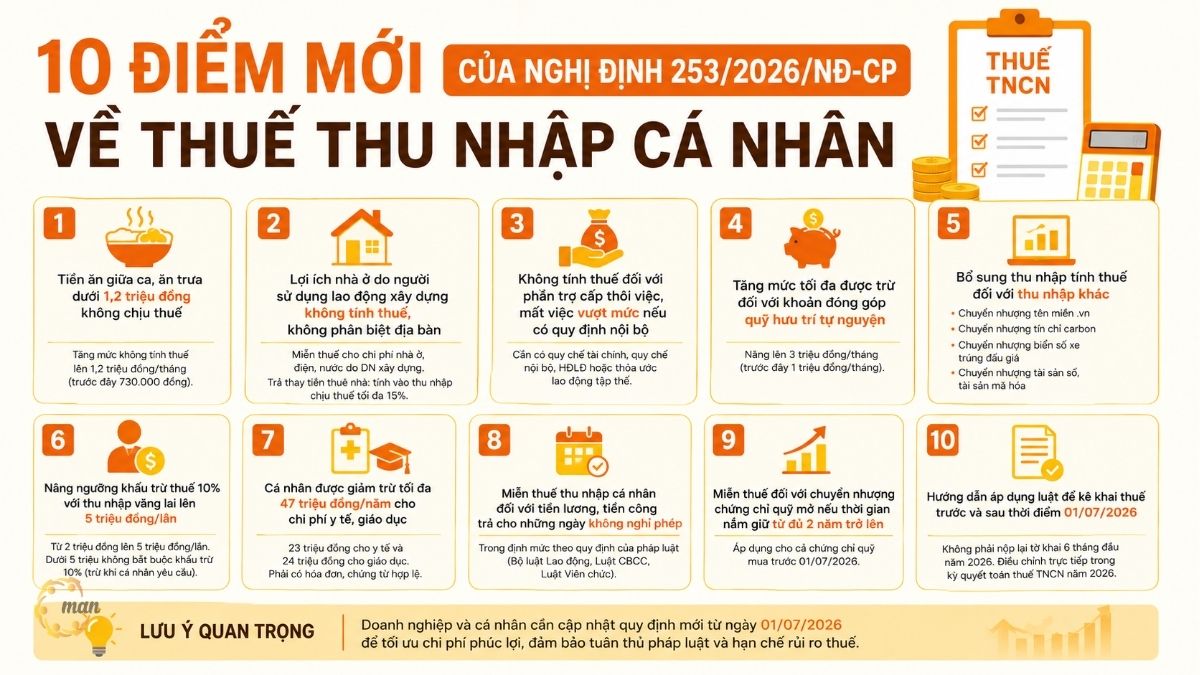
To help businesses and individual taxpayers keep up with the important changes, we have systematized and analyzed in detail the groundbreaking contents of the new Decree. Understanding these changes will not only help you comply with the law but also provide an opportunity to optimize operating costs and employee benefits. Below is an in-depth analysis of 10 new points of Decree 253/2026/ND-CP that accounting departments and business owners need to update immediately:
1. Meal allowances for breaks or lunch under 1.2 million VND are not subject to tax.
From July 1st, 2026, Decree 253/2026/ND-CP raises the limit. Meal allowances during work shifts and lunch allowances are not included in taxable income. The amount has increased to 1.2 million VND per month. Compared to the previous level of 730,000 VND, this is a necessary adjustment to accurately reflect the reality of living costs.
A solution from MAN – Master Accountant Network for businesses: Accountants need to review employment contracts and financial regulations. If the current support level is less than 1.2 million VND, businesses can consider adjusting it to increase actual benefits for employees without increasing their personal income tax burden.
Experts at MAN, with 30 years of experience, note that if a business organizes its own cooking, purchases meals, or distributes meal vouchers, the entire value is not included in taxable income. This is an optimal risk management approach, helping businesses avoid disputes over invoices and documentation related to cash transactions.
2. Benefits from housing built by the employer are not taxable, regardless of location.
Clause h, point 2, Article 8 of Decree 253/2026/ND-CP has removed geographical barriers to housing benefits. Previously, tax exemption only applied to housing in industrial zones or disadvantaged areas. Now, all housing, electricity, and water costs incurred by employers for their employees are not included in taxable income.
However, in the case of businesses paying rent on behalf of others, the amount included in taxable income is still limited to a maximum of 15% of the total taxable income generated at the unit. This is a point that the accounting department needs to be particularly careful about. Incorrectly calculating this 15% ratio is a common error that leads to tax arrears when an inspection team arrives.
3. Excess severance pay or unemployment benefits are not taxed if there are internal regulations in place.
The new regulation in point h, clause 3, Article 8 allows businesses to pay severance pay exceeding the legally stipulated amount without incurring personal income tax, provided that this payment is clearly stipulated in the financial regulations, internal regulations, labor contract, or collective labor agreement.
Experts at MAN, with 30 years of experience, affirm that this is an opportunity for businesses to attract talent with attractive severance packages. Our advice is that businesses need to standardize internal documentation immediately. If the expense is not stipulated in writing, the tax authorities will reject it and include it in tax calculations. taxable income, This creates significant tax risks for workers.
4. Increase the maximum deductible amount for voluntary retirement fund contributions.
Decree 253 raises the maximum deductible amount for voluntary retirement fund contributions to 3 million VND per month when calculating personal income tax, three times the previous 1 million VND. This change aims to encourage long-term savings and social security for workers.
From the perspective of MAN – Master Accountant Network, this policy provides businesses with additional tools to design competitive Total Rewards packages. Increasing this contribution not only offers tax benefits but also demonstrates the company's social responsibility towards its employees. Businesses need to update their payroll software to apply this 3 million VND limit starting from the July 2026 payroll period.
5. Adding other income to the taxable income.
Article 16 of Decree 253 adds new taxable income sources to more tightly manage money flows from the digital economy:
- Income from the transfer of national .vn domain names.
- Income from the transfer of greenhouse gas emission reductions and carbon credits.
- Income from the transfer of license plates won at auction.
- Income from the transfer of digital assets and crypto assets.
This addition shows that the tax authorities are stepping up control over income from non-traditional assets. For businesses operating in the technology sector, understanding these regulations is mandatory to avoid penalties for under-declaring or late-paying personal income tax.
6. Raise the tax deduction threshold for incidental income (under Article 10%) to 5 million VND per transaction.
The government has adjusted the threshold for paying temporary income (without a labor contract or with a contract of less than 3 months) from 2 million VND to 5 million VND per payment. If the income is less than 5 million VND, businesses are not required to deduct tax unless the individual requests it.
This change helps reduce the administrative burden for businesses that frequently use collaborators and freelancers. However, the risk lies in tracking payment frequency. Experts at MAN – Master Accountant Network note that if the total income of a freelancer is substantial, the individual must still file their own tax returns. Businesses should keep records of individual commitments to protect themselves during audits.
7. Individuals are entitled to a maximum deduction of 47 million VND per year for medical and educational expenses.
This is the most groundbreaking and humane change in Decree 253/2026/ND-CP. Resident individuals are entitled to a maximum deduction of 23 million VND for healthcare and 24 million VND for education.
A prerequisite for receiving tax deductions is having valid invoices and supporting documents. For medical expenses, a detailed expense statement as prescribed by the Ministry of Health is mandatory. Experts at MAN – Master Accountant Network have received many questions regarding the preparation of these documents. We recommend that employees proactively collect invoices from the moment expenses are incurred to avoid a shortage of documentation at the end of the year.
8. Exemption from personal income tax on salaries and wages paid for non-vacation days.
According to Article 26 of Decree 253, wages paid for days not taken as prescribed by the Labor Code, the Law on Civil Servants, and the Law on Public Employees will be exempt from personal income tax. Only the portion exceeding the legal limit will be subject to tax.
This is good news for both employees and businesses. Previously, many companies faced difficulties explaining these vacation pay payments to the tax authorities. With the new regulations, the line has become clearer. Businesses only need to retain the employment contract and work regulations to prove the validity of these payments.
9. Tax exemption for the transfer of open-ended fund certificates.
Decree 253 exempts personal income tax on income from the transfer of open-ended fund certificates if the holding period is 2 years or more. This policy aims to promote a long-term investment culture among Vietnamese people.
For individuals who purchased fund certificates before July 1, 2026, the holding period will still be counted towards this incentive. MAN – Master Accountant Network considers this a positive step by the regulatory body to develop the stock market. Investors should retain their securities account statements to prove the holding period when transferring ownership.
10. Guidance on applying the law for tax declaration before and after July 1, 2026
Article 70 clearly stipulates the transitional provisions: Businesses are not required to resubmit tax returns for the first six months of 2026. Adjustments will be made directly during the 2026 personal income tax final settlement period.
A solution from MAN – Master Accountant Network for the transition period: Businesses should proactively review their data for the first six months of the year to compare it with the new regulations. Although resubmission is not required, preparing the adjusted data will help the year-end settlement process run smoothly and avoid being caught off guard when dealing with tax authorities.
Expert opinion: Common risks and real-world experience
Through over 30 years of consulting experience at MAN – Master Accountant Network, I've found that the biggest mistake businesses make is "being slow to update new regulations into their internal policies." Decree 253/2026/ND-CP has opened up many benefits, but those benefits are only valid if they have a legal basis within the business.
Another risk is lax documentation. With the new medical and education deduction policies, invalid invoices could result in the entire deduction being disallowed. At MAN, we support our clients in establishing proper documentation archiving processes, helping them optimize their tax payments legally and securely.
Case Study: Optimizing Employee Benefits at Company X
Company X, with 200 employees, collaborated with MAN – Master Accountant Network to implement changes from Decree 253. Previously, the company only provided a meal allowance of VND 700,000 per month. After consultation, the company increased it to VND 1,200,000 per month, adjusted the severance pay regulations, and updated the list of medical deductions for employees.
As a result, after the 2026 tax year, the company not only reduced its tax risks but also increased employee satisfaction to 30%. This demonstrates that a deep understanding of tax regulations is a real competitive advantage for businesses.
Comparison table of old and new regulations
To easily track the important changes, here is a quick comparison table between the old and new regulations under Decree 253/2026/ND-CP. The compiled content focuses on points that have a major impact on businesses and taxpayers, helping you quickly identify the adjustments that need to be applied from July 1, 2026.
| Content | Old rules | New regulations (Decree 253) |
| Meal allowance | 730,000 VND/month | 1,200,000 VND/month |
| Current deduction threshold | 2,000,000 VND/time | 5,000,000 VND/time |
| Voluntary pension fund | 1,000,000 VND/month | 3,000,000 VND/month |
| Medical/Education Deductions | There are no regulations yet. | 47 million VND/year |
Conclude
The changes in Decree 253/2026/ND-CP mark a significant milestone, requiring businesses to be proactive in tax management. Understanding the regulations not only helps businesses avoid risks but also provides opportunities to optimize costs and employee benefits.
Tax services at MAN – Master Accountant Network
- Tax accounting services
- Tax consulting services
- Tax settlement services
- Tax reporting services
- VAT refund service
Service contact information at MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network, CPA Vietnam with over 30 years of experience in accounting, auditing, taxation, and corporate financial consulting.
Frequently Asked Questions about the 10 New Points of Decree 253/2026/ND-CP (FAQ)
Do I need to resubmit my tax return for the May 2026 period?
No. You only need to make adjustments to your 2026 tax return according to Article 70 of Decree 253.
Are children's medical expenses included in parents' tax deductions?
Yes. Decree 253 allows deductions for taxpayers and dependents, provided there is a valid invoice.
Will lunch expenses exceeding 1.2 million VND be subject to tax?
Yes, any difference exceeding 1.2 million VND will be included in taxable personal income.
What should a company do if it has paid severance pay in excess of the legal limit?
You need to immediately update this information in your internal regulations or collective bargaining agreement to legitimize the expenditure.
Are open-ended fund certificates purchased before July 1, 2026, tax-exempt?
Yes, if, at the time of transfer, you have held the shares for two years or more.




