Contractor tax on foreign loan interest is a key concern for chief accountants and CFOs when raising international capital. Misunderstanding regulations can lead to the risk of tax arrears, late payment penalties, and directly impact the company's cash flow. Therefore, a thorough understanding of tax policies is essential for sound financial management.
According to Circular 103/2014/TT-BTC, interest payments to non-resident entities are subject to contractor tax (FCT). Typically, the borrower in Vietnam will declare and pay this tax on behalf of the borrower. Depending on whether the loan agreement specifies Gross or Net interest, the business will determine the corresponding tax liability to ensure compliance with the law.
Summary of key aspects of Contractor Tax on Foreign Interest Loans
Contractor tax on foreign loan interest This is the tax obligation on interest accrued from loan agreements between Vietnamese businesses and foreign lenders. Clause 3, Article 12 of Decree 320/2025/ND-CP, interest payable Corporate income tax rate is 5% and is exempt from VAT. This regulation applies to all transactions involving interest and fees paid on loans taken out abroad, in order to ensure the nation's right to collect taxes.
The current legal basis for regulating contractor tax on foreign loan interest.
The enforcement of contractor tax on foreign loan interest is strictly regulated, from the Tax Administration Law to guiding circulars. Accountants need to be familiar with the tax rate changes over time to accurately reconcile long-term loan contracts. Applying the correct legal documents helps businesses optimize costs and avoid administrative errors.
Currently, Circular 103/2014/TT-BTC is the core document guiding tax obligations for foreign contractors. In addition, there are regulations regarding... VAT This is referenced in Circular 219/2013/TT-BTC. Specifically, Decree 320/2025/ND-CP, in Clause 3, Article 12, reaffirms the corporate income tax rate of 5% for this income.
| STT | Legal documents | Main adjustments |
| 1 | Circular 103/2014/TT-BTC | Instructions on how to calculate Corporate Income Tax on interest on foreign loans |
| 2 | Decree 320/2025/ND-CP | Corporate income tax regulations 5% regarding interest on loans (Clause 3, Article 12) |
| 3 | Circular 219/2013/TT-BTC | Regulations stipulate that interest on loans is exempt from VAT. |
| 4 | Tax Avoidance Agreement (DTA) | Tax exemption and reduction agreements between Vietnam and other countries. |
| 5 | Decree 132/2020/ND-CP | Regulations on the ceiling for interest expense deductions for affiliated companies. |
Composition and contractor tax rates of foreign loan interest.
Correctly identifying the tax components helps businesses accurately calculate the amount payable. For income from interest on loans, the tax liability is separated based on the nature of the financial services provided, according to current regulations.
Value Added Tax (VAT) on loan interest
Since January 1, 2014, according to Clause 8, Article 4 of Circular 219/2013/TT-BTC, credit granting services, including lending, are exempt from Value Added Tax (VAT). Therefore, when declaring contractor tax on foreign loan interest, businesses do not need to calculate VAT on this interest.
Prior to this, lending activities were subject to VAT under Circular 06/2012/TT-BTC. However, the new regulations have abolished this part to encourage a stronger flow of international investment into Vietnam.
Corporate Income Tax (CIT) on interest expenses.
Corporate Income Tax Foreign loan interest is a mandatory component of contractor tax. The corporate income tax rate calculated on revenue is 51% of 3% according to Article 13 of Circular 103/2014/TT-BTC. This regulation continues to remain stable in Clause 3, Article 12 of Decree 320/2025/ND-CP.
Taxable revenue includes interest on loans, loan fees, and other economic benefits received by the lender. Even if interest is added to the principal or converted into equity, the corporate income tax obligation (CIT 5%) must still be fully fulfilled according to the law.
See the detailed article here: Official Document 1918/CT-CS: Corporate Income Tax for Foreign Contractors 2026
Cases of contractor tax exemption for foreign loan interest (Japan focus)
Not all international loans are subject to taxation. Contractor tax on foreign interest may be exempt if a Double Taxation Avoidance Agreement (DTA) or a separate agreement between the governments applies. Loans from large Japanese financial institutions are a typical example.
Tax exemption for financial institutions wholly owned by the Government.
According to Article 11 of the Vietnam-Japan Agreement, interest expense is tax-exempt if the recipient is the Government or a central bank. Authorized organizations are also eligible for this preferential treatment.
For Japan, the list of tax-exempt organizations includes:
- Bank of Japan (BoJ), JBIC, JICA.
- Japan Export and Investment Insurance Organization (NEXI).
Tax exemption conditions are based on the contract signing period.
Official documents such as Circular 2623/TCT-HTQT have stipulated the timeframe for applying the contractor tax exemption for foreign loan interest. Specifically, loan interest paid to JBIC from contracts signed after April 1, 2012 will be exempt from tax in Vietnam.
For debts insured by NEXI, the tax exemption applies from November 26, 2015, as per Official Letter 1755/TCT-HTQT. This is an important preferential policy that helps reduce the financial burden for Vietnam-Japan cooperation projects.
| Insurance/Receiving Organization | Terms and Conditions | Legal basis |
| JBIC | The contract was signed on April 1, 2012. | Official Document 2623/TCT-HTQT |
| NEXI | The loan is insured (as of November 26, 2015) | Official Document 1755/TCT-HTQT |
| JICA | According to the ODA/Government agreement | Article 11 of the Agreement |
Methods for calculating and declaring contractor tax on foreign loan interest.
Determining the amount of tax payable depends on whether the contract specifies interest as net or gross. Accountants need to carefully read the payment terms to apply the correct conversion formula, ensuring no tax is underpaid.
Basic calculation formulas
The corporate income tax payable is calculated directly on the revenue paid to the contractor.
|
Corporate income tax amount = Taxable revenue x 5% |
If the contract specifies interest as Net, the business must convert it to Gross revenue before calculating the contractor tax on foreign interest:
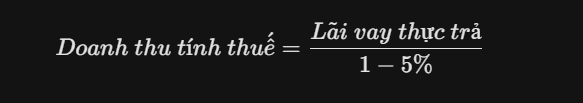
Real-life examples
A company borrows USD 1,000,000 at an interest rate of 6%/year, with net interest payments. The actual interest paid is USD 60,000. The taxable revenue for contractor purposes is the foreign loan interest.i That is: 60,000 / 0.95 = 63,157.89 USD. The corporate income tax paid on behalf of the company will be 3,157.89 USD.
See more articles at: New draft regulations on contractor tax on foreign loan interest in 2025.
Important notes regarding administrative procedures and deadlines.
To qualify for tax exemptions and reductions, businesses must submit their exemption/reduction application to the directly managing tax authority. Failure to submit the required documents may result in the loss of benefits under the Agreement.
Tax exemption notification file under the Agreement
The application includes a notification form (Form 01/HTQT) and a consular-legalized Certificate of Residence for the foreign contractor. Additionally, copies of the loan agreement and interest payment receipts are required for verification.
Deadline for filing and paying taxes
The deadline for filing contractor tax returns for foreign loan interest is the 10th day from the date the tax liability arises. Late filing will result in administrative penalties according to Law No. 38/2019/QH14 on Tax Administration.
Conclude
Taxing foreign loan interest requires a deep understanding of international laws and agreements. Up-to-date regulations such as Decree 320/2025/ND-CP help businesses operate transparently and optimize financial costs effectively.
If you need assistance with contract review, tax filing, or exemption procedures, MAN – Master Accountant Network Always ready to partner with you. We offer comprehensive solutions for:
- Specialized auditing and tax accounting services.
- Professional tax consulting and tax settlement services.
- Fast and accurate tax reporting and refund services.
Contact us now! MAN – Master Accountant Network To receive advice from a team of leading experts, helping businesses achieve sustainable growth.
Service contact information at MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- Email: man@man.net.vn
Content production by: Mr. Le Hoang Tuyen – Founder & CEO MAN – Master Accountant Network, Vietnamese CPA Auditor with over 30 years of experience in Accounting, Auditing and Financial Consulting.
Frequently Asked Questions about Contractor Tax on Foreign Loan Interest
Yes. All forms of income offsetting are considered the point at which taxable contractor revenue from foreign loan interest arises.
Yes, if the contract stipulates a net price and the business has documentation proving tax payment on behalf of the contractor as required by regulations.
No. The tax rate remains stable at 5% on taxable revenue to ensure consistency in management. Is compounded interest subject to contractor tax?
If a business pays the contractor's tax on behalf of the contractor, is this expense deductible?
Does Decree 320/2025/ND-CP change the interest rate on loans?